Researched and drafted with AI assistance · reviewed and edited by Jason D. Keys
Two claims that deserve a hearing
Two propositions have circulated in hard-money and precious-metals commentary for the better part of three decades, and both are usually dismissed without examination by people who have not looked at the record.
The first is that the prices of gold and silver are systematically suppressed through the futures markets — that paper contracts written in volumes unrelated to physical supply are used to hold the metal price below where physical demand would otherwise place it.
The second is that a government body, known informally as the Plunge Protection Team, intervenes to support the equity market during periods of decline.
This essay examines both against the documentary record, because the framework's position is that a claim deserves the courtesy of evidence rather than the convenience of dismissal. What follows finds the first claim substantially vindicated in a form that does not support the conclusion it is usually offered for, and the second unsupported in its operative element and largely accurate in its incidental one.
It then argues that the manipulation frame has been analytically expensive for the community that holds it — not because the intuition is wrong, but because searching for secrecy causes one to miss something considerably larger that is hiding in plain sight, measured in the peer-reviewed literature, and disclosed in fund prospectuses.
What is actually proven
Manipulation of the precious metals futures markets is not a theory. It is a matter of court record, admitted conduct, and federal prison sentences.
In September 2020 the Commodity Futures Trading Commission issued an order against JPMorgan Chase & Company and its subsidiaries requiring payment of $920.2 million — the largest amount of monetary relief ever imposed by the agency — comprising a civil monetary penalty of $436,431,811, restitution of $311,737,008, and disgorgement of $172,034,790. The order found manipulative and deceptive conduct and spoofing that spanned at least eight years and involved hundreds of thousands of spoof orders in precious metals and United States Treasury futures contracts on the Commodity Exchange, the New York Mercantile Exchange, and the Chicago Board of Trade. 1
JPMorgan admitted committing wire fraud in connection with unlawful trading in precious metals futures and in Treasury futures and the secondary cash market for Treasury notes and bonds, and entered a three-year deferred prosecution agreement. 2 The Justice Department stated the conspiracy on the metals desk ran from March 2008 to August 2016 and involved fifteen traders across two desks. 3
The individuals were prosecuted. Michael Nowak, global head of the precious metals desk, and Gregg Smith, his top gold trader, were convicted in August 2022 of wire fraud affecting a financial institution, commodities fraud, attempted price manipulation, and spoofing. 4 In August 2023 they were sentenced — Nowak to one year and one day, Smith to two years, with prosecutors describing Smith as "the most prolific spoofer that the government has prosecuted to date." 5 Four other JPMorgan metals traders were convicted or pleaded guilty in related matters, and former Deutsche Bank and Bank of America traders received one-year sentences in parallel cases. 2 5
Anyone who has argued for twenty years that precious metals prices are manipulated has been vindicated on the fact of manipulation. The framework states that plainly, because the same commentators were told for most of that period that they were imagining things.
But the mechanism does not support the suppression thesis, and the distinction is the substance of this section.
Prosecutors established that Nowak and Smith "moved precious-metals prices up and down for profit." 6 The method was to place genuine orders, follow them with large orders never intended to execute, and then either sell into the artificially inflated price or buy at the artificially deflated one. 7 The scheme was bidirectional by design, because its object was trading profit on the desk's own positions, not a price level.
It was also tactical in duration. Spoofing operates over seconds and minutes — the interval between placing a deceptive order and canceling it. It is not a mechanism capable of holding a price below its clearing level for years.
Two further details matter for calibration. Both defendants were acquitted on the RICO charges, which is the theory that would have established the desk as a criminal enterprise in the organized-crime sense. 4 And a third defendant, the desk's salesman, was acquitted on all counts. 4 Prosecutors brought the most aggressive available theory and the jury declined it while convicting on the substantive conduct.
So: manipulation, proven. Sustained unidirectional suppression in service of a policy objective, not established by this record.
What the Working Group actually is
The second claim can be settled more quickly, because the primary document is short and public.
Executive Order 12631 was signed by President Ronald Reagan on March 18, 1988, five months after the October 19, 1987 crash, and published at 53 Federal Register 9421. 8 It establishes a Working Group on Financial Markets composed of four members: the Secretary of the Treasury or his designee, who chairs it; the Chairman of the Board of Governors of the Federal Reserve System or his designee; the Chairman of the Securities and Exchange Commission or his designee; and the Chairman of the Commodity Futures Trading Commission or her designee. 8
Its stated purpose is "enhancing the integrity, efficiency, orderliness, and competitiveness of our Nation's financial markets and maintaining investor confidence." 9
The name "Plunge Protection Team" does not appear in the order. It was applied by The Washington Post in February 1997, nine years after the body was created. 9
The order establishes no appropriation, no trading desk, and no authority to purchase securities. There is no public evidence that the Working Group directly buys stocks or futures; its documented role consists of coordination, policy recommendation, and communication, with activity concentrated in periods of disorderly decline — 1998, 2008, and March 2020. 10
The framework's assessment: the body exists, is correctly named by its critics, met during the crises they say it met during, and does not do the specific thing the claim requires. The operative allegation — direct equity purchase to support prices — is unsupported by the public record.
Why the frame is expensive
Here the essay turns, and the argument is directed with some sympathy at the community that holds these claims.
The manipulation frame asks: is someone secretly doing this? It is an inquiry into concealment. It looks for a hidden actor, a covert desk, an unrevealed instruction.
That inquiry has a structural weakness. Secrecy imposes a hard ceiling on scale. A scheme that must remain concealed can involve only as many participants as can be trusted to stay silent, can persist only as long as it escapes detection, and must be abandoned when discovered. The JPMorgan desk is the illustrative case: fifteen traders, eight years, and then indictments, a record penalty, and prison.
Now consider the proportion. That entire eight-year scheme — the largest such penalty in the history of the CFTC, across precious metals and Treasury futures — resulted in $920.2 million in total monetary relief.
The Investment Company Institute reports that assets held in 401(k) plans alone stood at $10.1 trillion at the end of 2025. 11
The full penalty for the largest proven market manipulation case in modern American financial history amounts to approximately 0.009 percent of the money sitting in 401(k) plans.
That comparison requires no estimation and no assumption. It is two sourced figures divided. And it suggests the question worth asking is not who is hiding something, but what is operating openly at a scale where concealment would be unnecessary.
The better question, and the measured answer
The better question is this: what price-setting mechanisms operate at scale without requiring secrecy?
That question has been answered in the peer-reviewed literature, and the answer is more consequential than the allegation it replaces.
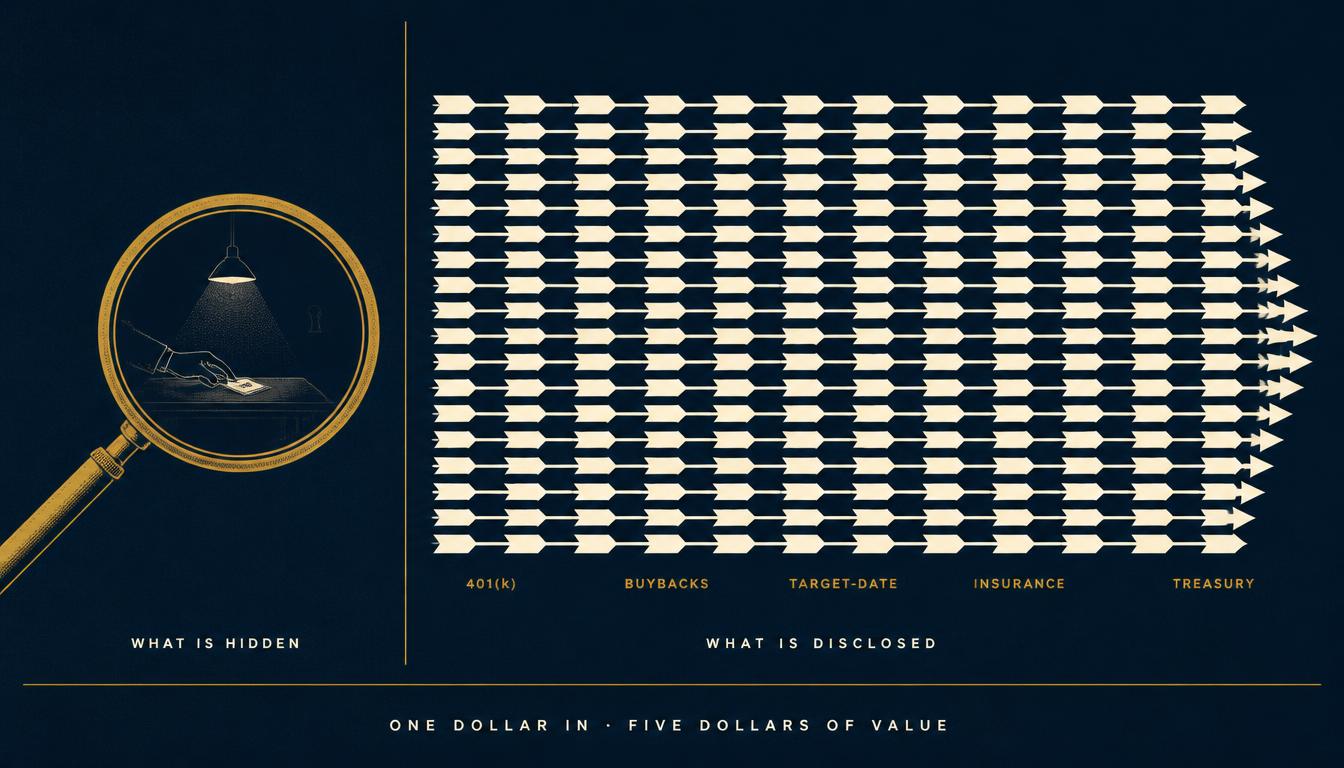
Xavier Gabaix of Harvard and Ralph Koijen of the University of Chicago Booth School of Business published In Search of the Origins of Financial Fluctuations: The Inelastic Markets Hypothesis as National Bureau of Economic Research Working Paper 28967. Using granular instrumental variables applied to sector-level flow-of-funds data covering 1993 through 2020, they find that investing one dollar in the stock market increases the market's aggregate value by approximately five dollars. 12 13
The multiplier is estimated at approximately 5, with a range of 3 to 8 across specifications. 14 The implied price elasticity of aggregate equity demand is approximately negative 0.2 — a five percent rise in price reduces quantity demanded by one percent — against a value nearer negative 20 that conventional models of rational investors would predict. 15 The effect is linear and symmetric: selling one dollar of equities reduces aggregate value by approximately five dollars. 16 Flows account for more than a third of market fluctuation, and equity returns are more than twice as volatile as fundamental information implies they should be. 13
The mechanism is stated plainly in the paper, and it is the whole of this essay's argument. Households allocate capital to institutions "which are fairly constrained, for example operating with a mandate to maintain a fixed equity share or with moderate scope for variation in response to changing market conditions." 12 The marginal holders of equity — index funds, pension funds, insurance companies — operate under mandates fixing their allocations within narrow bands. When aggregate demand shifts, few participants can absorb the change, and prices must move substantially to clear. 14
One detail from the paper's history belongs in this essay because it establishes how far the profession's intuition sat from the measured result. Before publishing, Gabaix and Koijen surveyed 102 academic researchers in economics and finance, asking what one dollar entering the stock market would do to prices. Just over half predicted no price effect at all. Of those who thought there would be some effect, exactly three said the multiplier would exceed one. 13
The measured answer was five.
The mandated bid, as this catalog has already documented it
The significance of the Gabaix-Koijen result for this framework is that every channel supplying that mandated bid has already been documented across prior installments, without the framework having recognized that they constitute a single phenomenon.
Retirement flows. Article 48 traced the path from an American paycheck to an asset purchase: automatic payroll deduction, into target-date and index funds selected by a plan administrator, buying an index in which the largest seven constituents represent roughly a third of value. Eighty million workers, every two weeks. The Investment Company Institute reports $10.1 trillion in 401(k) assets at year-end 2025 and $14.2 trillion across all employer-based defined contribution plans, with mutual funds holding 57 percent of 401(k) assets — $3.4 trillion in equity funds and $1.6 trillion in hybrid funds including target-date products. 11 Individual retirement accounts held a further $19.2 trillion. Total United States retirement assets reached $49.1 trillion. 11 EBRI and ICI tabulations find that equity securities — equity funds, the equity portion of balanced funds, and company stock — have represented roughly 63 percent of 401(k) participants' assets. 17
Corporate buybacks. Article 41 documented $9.2 trillion in real terms spent by United States listed corporations on share repurchases between 2012 and 2021, with buybacks rising from approximately 11 percent of total shareholder returns in 1982 to approximately 55 percent by 2021. A repurchase authorization is a mandate: the board approves an amount, and execution is delegated and largely price-insensitive within its parameters.
Leveraged exchange-traded products. Article 46 established that daily-rebalanced leveraged funds must adjust exposure at every close to maintain their stated multiple — mechanically buying after gains and selling after losses, with no discretion whatsoever. That article documented eleven such products appearing on a single security within days of its listing.
Insurance general accounts. Article 48 documented $11.0 trillion in United States life insurer assets against $10.6 trillion in liabilities, with allocations governed by capital charges and statutory constraints rather than by any manager's view of value.
And now the sovereign issuer. Articles 51 and 52 documented the Treasury doubling its long-end buyback capacity on August 19, 2026, placing a scheduled, price-insensitive buyer into the market for its own securities.
Not one of these requires secrecy. Every one is disclosed. Together they constitute the marginal bid across the two largest asset markets in the world.
An estimate, labeled as one
The framework would like to state the magnitude of the retirement channel precisely and cannot, because aggregate annual contribution flows across all defined contribution plans and individual retirement accounts are not published in a single authoritative series. What follows is therefore an estimate, presented with its assumptions exposed, and the framework flags it as the weakest quantitative claim in this essay.
Taking the sourced figures of $14.2 trillion in employer-based defined contribution assets and $19.2 trillion in individual retirement accounts, 11 and assuming gross annual contributions in the range of 3 to 5 percent of the defined contribution asset base — a range consistent with a mature system in which contributions are supplemented by investment growth, but which the framework has not verified against a primary series — implies annual defined contribution inflows on the order of $425 billion to $710 billion.
Applying the roughly 63 percent equity share 17 gives equity-directed flows of approximately $270 billion to $450 billion annually from defined contribution plans alone, before any contribution from individual retirement accounts.
At the Gabaix-Koijen central multiplier of 5, that implies an annual aggregate price impact of roughly $1.3 trillion to $2.2 trillion. At the low end of their range the figure is $0.8 to $1.4 trillion; at the high end, $2.2 to $3.6 trillion.
Every element of that calculation after the first two sourced figures is an assumption, and the framework invites correction. What survives even the most conservative treatment is the comparison with which the previous section began: the largest proven manipulation scheme in modern American financial history carried a total penalty of $920.2 million. The mandated retirement bid moves prices by amounts three to four orders of magnitude larger, every year, lawfully, on a payroll schedule.
Why Menger makes this the more serious condition
The framework's objection to the mandated bid is not that it is illegitimate. Retirement saving is good, automatic enrollment has raised participation, and index funds have reduced costs enormously for ordinary savers. Nothing here argues otherwise.
The objection is epistemic, and Menger supplies its precise form.
Carl Menger's 1892 account of the origin of money describes an institution that emerged without design, through individuals seeking to improve their own trading position by moving toward more saleable commodities. 18 The reason that account matters beyond monetary history is what it implies about prices generally: a market price carries information because it is the residue of discretionary choices made by parties with something at stake, each acting on knowledge no central observer possesses.
A mandated buyer makes no such choice. An index fund receiving an inflow does not form a view on whether the constituents are attractively priced. It buys in proportion to existing weights because its prospectus requires it. A target-date fund rebalancing toward its glidepath does not assess value. A leveraged product adjusting at the close does not either. A repurchase program executing an authorization operates within parameters set months earlier.
None of these is manipulating anything. Each is doing exactly what it disclosed it would do. But collectively they constitute a bid that forms no marginal valuation, and when the marginal bid forms no valuation, the resulting price is not a Mengerian price. It is not corrupted. It is something else — the outcome of scheduled flows meeting a constrained float.
This is why the measured elasticity is negative 0.2 rather than negative 20. Elasticity is discretion, expressed numerically. An elasticity of negative 0.2 describes a market in which almost nobody at the margin is positioned to say no.
And that is a more serious condition than a conspiracy, for the reason the previous sections developed: it requires no secrecy, faces no enforcement risk, involves no culpable party, and therefore has no natural termination. The JPMorgan desk was indicted. A prospectus cannot be.
The bid that withdrew and the bid that cannot
Article 52 of this catalog argued that Fekete's marginal bondholder — the agent whose arbitrage between gold and bonds disciplines the rate of interest — retains one form of discipline under an irredeemable standard that Fekete did not develop. Unable to flee into a superior asset, he can still decline to appear at the auction. That essay pointed to the five-year Treasury auction of September 23, 2026 clearing at 5.033 percent, the highest since 2006 and more than three basis points above expectations with weak foreign participation, and to Treasury's response of becoming the buyer itself.
Gabaix and Koijen have measured the mirror image: what a market looks like when the marginal buyer has no option to withdraw.
Place the two together and the framework arrives at its synthesis:
The Treasury market and the equity market are currently in opposite conditions produced by the same structural cause — the composition of the marginal bid.
In Treasuries, the discretionary bidder is stepping back, the price is moving against the issuer, and the issuer has inserted itself to fill the gap. In equities, the bidder is mandated and cannot step back, which is why a dollar of inflow moves five dollars of market value and why returns are twice as volatile as fundamentals imply.
Neither condition requires anyone to be doing anything improper. Both are consequences of who holds the marginal position and whether that holder is permitted to exercise judgment.
What would falsify this
The framework states the conditions under which it would abandon this argument.
If the Gabaix-Koijen multiplier fails to replicate. The result has been examined and broadly supported — Bouchaud reconciled it with order-flow microstructure theory, 19 and subsequent econometric work using alternative instruments found a point estimate of negative 0.05 for the elasticity with evidence of investor-level heterogeneity. 15 But it is one empirical finding, and a well-identified study recovering an elasticity near the theoretical negative 20 would substantially damage this essay.
If mandated flows prove to be price-elastic in aggregate. The argument assumes inflows continue regardless of valuation. A sustained period in which retirement contributions fall materially in response to high prices, rather than in response to unemployment, would indicate more discretion in the channel than the framework has attributed to it.
If documentary evidence of Working Group securities purchases emerges. The framework has stated that the operative allegation is unsupported by the public record. Evidence of a trading facility would falsify that and require revision.
The framework notes what would not falsify it: further prosecutions for spoofing. Additional cases would confirm what is already established and would say nothing about the scale question this essay raises.
The framework's reading
The hard-money community has spent decades arguing that market prices are not what they appear to be, and has been treated as credulous for saying so. On the narrow question of whether manipulation occurs, the court record has vindicated them, and their critics owe them an acknowledgment.
But the frame within which they made the argument has cost them the larger finding. By asking who is concealing something, that literature has spent its attention on a mechanism bounded by the requirements of secrecy — fifteen traders, eight years, $920.2 million — while the open, disclosed, legally mandated bid moved prices by amounts several orders of magnitude greater, on a schedule set by payroll systems.
This catalog has argued across fifty-two prior installments that the substitute layer interposes claims between savers and the assets those claims represent, and that the essential analytical discipline is distinguishing a claim from the thing it names. The parallel discipline here is distinguishing a price from a number occupying the position where a price would be.
Menger's account holds that a price is informative because discretionary participants produce it. Gabaix and Koijen have measured a market in which the marginal participant has an elasticity of negative 0.2 — which is to say, almost no discretion at all.
You do not need a conspiracy to arrive at that. You need only mandates, and those were adopted in the open, for reasons that were mostly good, by people who disclosed exactly what they were going to do.
Sources
Note on the estimate in "An estimate, labeled as one." The assumption that gross annual defined contribution inflows run 3 to 5 percent of the defined contribution asset base is the framework's own and is not drawn from a published series. It is offered to establish an order of magnitude and should be treated as the weakest quantitative claim in this essay. The comparison opening the section "Why the frame is expensive" — $920.2 million against $10.1 trillion in 401(k) assets — rests entirely on the two sourced figures at 1 and 11 and requires no assumption.
Framework cross-references. Article 41 (corporate buybacks 1982–2021 and the $9.2 trillion repurchase figure); Article 46 (index concentration, leveraged exchange-traded product rebalancing, and the size hierarchy of markets); Article 48 (the flow of funds from payroll deduction to asset purchase; life insurer balance sheet constraints); Article 51 (Treasury long-end buyback mechanics); Article 52 (Fekete's marginal bondholder, the option to withdraw the bid, and the 23 September 2026 five-year auction).
Footnotes
-
Commodity Futures Trading Commission. "CFTC Orders JPMorgan to Pay Record $920 Million for Spoofing and Manipulation." Release Number 8260-20, 29 September 2020. https://www.cftc.gov/PressRoom/PressReleases/8260-20 — "JPM is required to pay a total of $920.2 million—the largest amount of monetary relief ever imposed by the CFTC—including the highest restitution ($311,737,008), disgorgement ($172,034,790), and civil monetary penalty ($436,431,811) amounts." Also the source for the eight-year span, the hundreds of thousands of spoof orders, and the venues (COMEX, NYMEX, CBOT). ↩ ↩2
-
U.S. Department of Justice. "Ex-Wall Street Trader Convicted of Fraud in Precious Metals Spoofing Scheme." Office of Public Affairs. https://www.justice.gov/archives/opa/pr/ex-wall-street-trader-convicted-fraud-precious-metals-spoofing-scheme — Source for JPMorgan's September 2020 admission of wire fraud in precious metals futures and in Treasury futures and the secondary cash market for Treasury notes and bonds, the three-year deferred prosecution agreement, and the related convictions and guilty pleas of Smith, Nowak, Edmonds and Trunz. ↩ ↩2
-
"JPMorgan slammed with $920m penalty over market manipulation." Al Jazeera, 29 September 2020. https://www.aljazeera.com/economy/2020/9/29/bbjpmorgan-admits-spoofing-by-15-traders-2-desks-in-record-deal — Source for the conspiracy period of March 2008 to August 2016, the fifteen traders across two desks, and the RICO charging theory. ↩
-
"Two Former JPMorgan Precious Metals Traders Convicted in Spoofing Scheme." Willkie Farr & Gallagher LLP client memorandum, August 2022. https://www.willkie.com/publications/2022/08/two-former-jpmorgan — Source for the 10 August 2022 convictions of Nowak and Smith on wire fraud, attempted price manipulation, commodities fraud and spoofing; their acquittal on the RICO counts; and the acquittal of Jeffrey Ruffo on all charges. ↩ ↩2 ↩3
-
"Ex-JPMorgan Gold Traders Get Prison for 'Prolific Spoofing.'" Bloomberg Law, August 2023. https://news.bloomberglaw.com/litigation/jpmorgans-most-prolific-spoofer-gets-two-years-in-prison-1 — Source for the August 2023 sentences (Nowak one year and one day, Smith two years, before U.S. District Judge Edmond Chang), the characterization of Smith as "the most prolific spoofer that the government has prosecuted to date," and the one-year sentences given to former Deutsche Bank and Bank of America traders. ↩ ↩2
-
"JPMorgan Gold Traders Found Guilty After Long Spoofing Trial." Bloomberg, 10 August 2022. https://www.bloomberg.com/news/articles/2022-08-10/jpmorgan-precious-metals-traders-found-guilty-in-spoofing-trial — "Prosecutors presented evidence that included detailed trading records, chat logs and testimony by former co-workers who 'pulled back the curtain' on how Nowak and Smith moved precious-metals prices up and down for profit from 2008 to 2016." ↩
-
Willkie Farr & Gallagher LLP (as 4) — "Defendants profited off this scheme by placing genuine orders prior to these false orders and then either selling at the artificially inflated price or buying at an artificially deflated price." ↩
-
Executive Order 12631 of March 18, 1988, "Working Group on Financial Markets." 53 Federal Register 9421; 3 CFR, 1988 Comp., p. 559. National Archives. https://www.archives.gov/federal-register/codification/executive-order/12631.html — Primary source for the establishment date, the four-member composition, and the designation of the Secretary of the Treasury as chairman. Text also available via the American Presidency Project at https://www.presidency.ucsb.edu/documents/executive-order-12631-working-group-financial-markets ↩ ↩2
-
"Working Group on Financial Markets." Wikipedia, citing Executive Order 12631 and "Plunge Protection Team," The Washington Post, 23 February 1997. https://en.wikipedia.org/wiki/Working_Group_on_Financial_Markets — Source for the order's stated purposes as quoted and for the origin of the informal name in the 1997 Washington Post article. ↩ ↩2
-
"Plunge Protection Team: What They Do." TradingSim, 6 May 2026. https://www.tradingsim.com/blog/the-plunge-protection-team — "There is no public evidence that the Working Group directly buys stocks or futures. Its documented role is coordination, policy recommendations, and communication." Also the source for the observation that activity concentrates during disorderly declines (1998, 2008, March 2020) and that direct equity purchases are not part of the documented toolkit. ↩
-
Investment Company Institute. "Quarterly Retirement Market Data, Fourth Quarter 2025." https://www.ici.org/statistical-report/ret_25_q4 — Source for total United States retirement assets of $49.1 trillion; $14.2 trillion in all employer-based defined contribution plans of which $10.1 trillion in 401(k) plans; $19.2 trillion in individual retirement accounts; and mutual funds at 57 percent of 401(k) assets ($5.8 trillion), with $3.4 trillion in equity funds and $1.6 trillion in hybrid funds including target-date funds. First-quarter 2026 figures ($9.9 trillion in 401(k) assets, $13.8 trillion in defined contribution plans, $18.2 trillion in IRAs) appear at https://www.ici.org/statistical-report/ret_26_q1 ↩ ↩2 ↩3 ↩4 ↩5
-
Gabaix, Xavier and Ralph S. J. Koijen. "In Search of the Origins of Financial Fluctuations: The Inelastic Markets Hypothesis." NBER Working Paper 28967, 2021. https://www.nber.org/papers/w28967 — "Households allocate capital to institutions, which are fairly constrained, for example operating with a mandate to maintain a fixed equity share or with moderate scope for variation in response to changing market conditions. As a result, the price elasticity of demand of the aggregate stock market is small, and flows in and out of the stock market have large impacts on prices. Using the recent method of granular instrumental variables, we find that investing $1 in the stock market increases the market's aggregate value by about $5." ↩ ↩2
-
"Why Are Financial Markets So Volatile?" Chicago Booth Review, 2 February 2022. https://www.chicagobooth.edu/review/why-are-financial-markets-so-volatile — Source for the finding that flows amplify volatility such that stock returns are more than twice as volatile as fundamental information implies, for the data period of 1993 to 2020, and for the pre-publication survey: "they asked 102 academic researchers in economics and finance to predict what every $1 entering the stock market would do to prices. The prevailing view, held by just over half of respondents, was that it would have no price effect. Of those who said it would have some effect, only three people said it would have a multiplier effect greater than one." ↩ ↩2 ↩3
-
"Extensions to the Wealth Tax Neutrality Framework," arXiv:2603.05277, section 5.2. https://arxiv.org/pdf/2603.05277 — Source for the multiplier range of 3 to 8 across specifications and for the summary of the mechanism: "The low elasticity arises because the marginal holders of equity—index funds, pension funds, insurance companies—operate under mandates that fix their equity allocations within narrow bands." ↩ ↩2
-
"Heterogeneity-robust granular instruments," arXiv:2304.01273, section 6.2. https://arxiv.org/pdf/2304.01273 — Source for the statement of the Gabaix-Koijen elasticity (a five percent price increase reducing quantity demanded by one percent, an elasticity of −0.2), the contrast with a conventional expectation nearer −20, and an independent replication finding a point estimate of −0.05 with evidence of investor-level heterogeneity. ↩ ↩2
-
Gabaix and Koijen, working paper text: "The price impact is linear and symmetric: selling $2 worth of equities (buying $2 worth of bonds) decreases the [aggregate market value proportionally]." Cowles Foundation copy at https://cowles.yale.edu/sites/default/files/2022-10/SSRN-id3686935.pdf ↩
-
Employee Benefit Research Institute and Investment Company Institute, Participant-Directed Retirement Plan Data Collection Project. https://www.ebri.org/docs/default-source/pbriefs/ebri_ib_526_401kxsec.4mar21.pdf — "Altogether, equity securities — equity funds, the equity portion of balanced funds, and company stock — represented 63 percent of 401(k) plan participants' assets at year-end 2018." See also ICI Research Perspective, Vol. 31 No. 6, August 2025, https://www.ici.org/system/files/2025-08/25-per31-06.pdf, which applies the same definition including the equity portion of target-date funds. ↩ ↩2
-
Menger, Carl. "On the Origins of Money." Economic Journal, Vol. 2 (1892), pp. 239–255. Translated by Caroline A. Foley. ↩
-
Bouchaud, Jean-Philippe. "The Inelastic Market Hypothesis: A Microstructural Interpretation." Capital Fund Management and Académie des Sciences, January 2022. arXiv:2108.00242. https://arxiv.org/pdf/2108.00242 — Reconciles the inelastic markets hypothesis with order-driven microstructure theory and derives a prediction for the Gabaix-Koijen multiplier from latent liquidity theory. ↩
Related essays
The Hormuz Yuan Toll: A Spontaneous Mengerian Event
Iran charging yuan tolls at Hormuz during wartime, India paying for Russian crude outside the dollar, the 1974 US-Saudi economic commission expiring unreplaced — these are not geopolitical conspiracies. They are textbook Mengerian monetary evolution, happening in real time.
Monetary Power to the People
Money is a medium in McLuhan's sense — an extension of the human body that amplifies the capacity for exchange. Understanding this is the critical path to navigating the financial disruptions of the present age.
The Saleability Audit of Bitcoin: What Menger Would Say in 2026
Bitcoin maximalists insist Bitcoin is the most saleable monetary good ever created. Skeptics insist it doesn't work for the African villager or the rural Chinese citizen the maximalists invoke. Both positions miss what Menger's framework actually says when applied carefully. The audit produces uncomfortable results in both directions — Bitcoin scores remarkably well on some criteria and remarkably poorly on others — and the actual ground-truth of crypto adoption in emerging markets in 2026 is something neither camp accurately describes.