The Friction Nobody Designed
The recurring claim is that the next liquidity event will be used to impose central bank digital currency and to seize bank deposits. Forum #54 examines the documentary record and finds the claim mistaken in its structure while resting on facts that are almost entirely accurate. Bail-in has been European Union law for a decade: bail-in of at least eight percent of total liabilities and own funds is a precondition for accessing the Single Resolution Fund, and the Single Resolution Board defines bail-inable deposits as all deposits other than covered deposits below one hundred thousand euros. Nothing needs to be imposed, because the authority already exists. What a BIS unified ledger would change is not the authority but the latency — the interval between a resolution decision and its execution. That interval was designed by no one, protects no one deliberately, and is exactly the kind of thing an efficiency improvement removes without discussion. This issue covers the interval since #016 and the seven Watching the Cracks essays published across it.
Full analysis: newaustrianeconomics.com/forum/54-contingent-actions-unified-ledger-bail-in-power
Welcome to Issue #017 of The Dispatch. Each Monday, this letter takes one situation from the week's news and reads it through the lens of Carl Menger and Antal Fekete — paired with a foundational concept, the dashboard, the framework's prediction record, and a piece from the archive. If someone forwarded this to you, subscribe here.
The Lens
A recurring proposition in hard-money commentary holds that the next serious liquidity event will be used as the occasion to introduce central bank digital currency, and that depositors will discover their balances converted into bank equity without their consent.
Forum #54 examines the documentary record on both halves and arrives at an unusual finding: the claim is mistaken in its structure and almost entirely accurate in its facts.
Bail-in is not a proposal. It has been European Union law since the Bank Recovery and Resolution Directive, under which bail-in of at least eight percent of total liabilities and own funds is a precondition for accessing the Single Resolution Fund. The Single Resolution Board defines the relevant category in its own working paper without euphemism: "Bail-inable deposits: These are all deposits with the exception of covered deposits." Covered deposits are generally those below one hundred thousand euros. Every euro above that threshold sits inside the bail-inable category by statutory definition. The same working paper concluded that under the existing creditor hierarchy, deposit guarantee schemes would rarely be able to support resolution without bailing in depositors — and that bail-in is the prevalent preferred resolution strategy across the institutions the Board supervises.
Nothing needs to be imposed during a crisis, because the authority has existed for a decade and was exercised in Cyprus in 2013, before any central bank digital currency existed anywhere.
This issue covers the interval since Issue #016, across which the catalog published seven essays — Forum #48 through #54, the Watching the Cracks series. They were written separately and they converge on one observation, which Forum #54 states most sharply and which organizes this letter: the mechanisms that matter in this system are not concealed. They are published, argued for on their merits, and adopted for reasons that are mostly good. What goes unexamined is not their existence but their scope.
Lead Essay: Latency, Not Authority
Forum #54's substantive contribution is a distinction the policy literature does not draw, and stating it precisely matters.
The fear says a unified ledger with central bank digital currency would give authorities the power to take deposits. That is wrong, and it is wrong in a way that has cost the argument its force. The power exists. It has a defined threshold of eight percent, a defined scope covering all deposits above the guarantee limit, a defined hierarchy, and status as the prevalent preferred strategy.
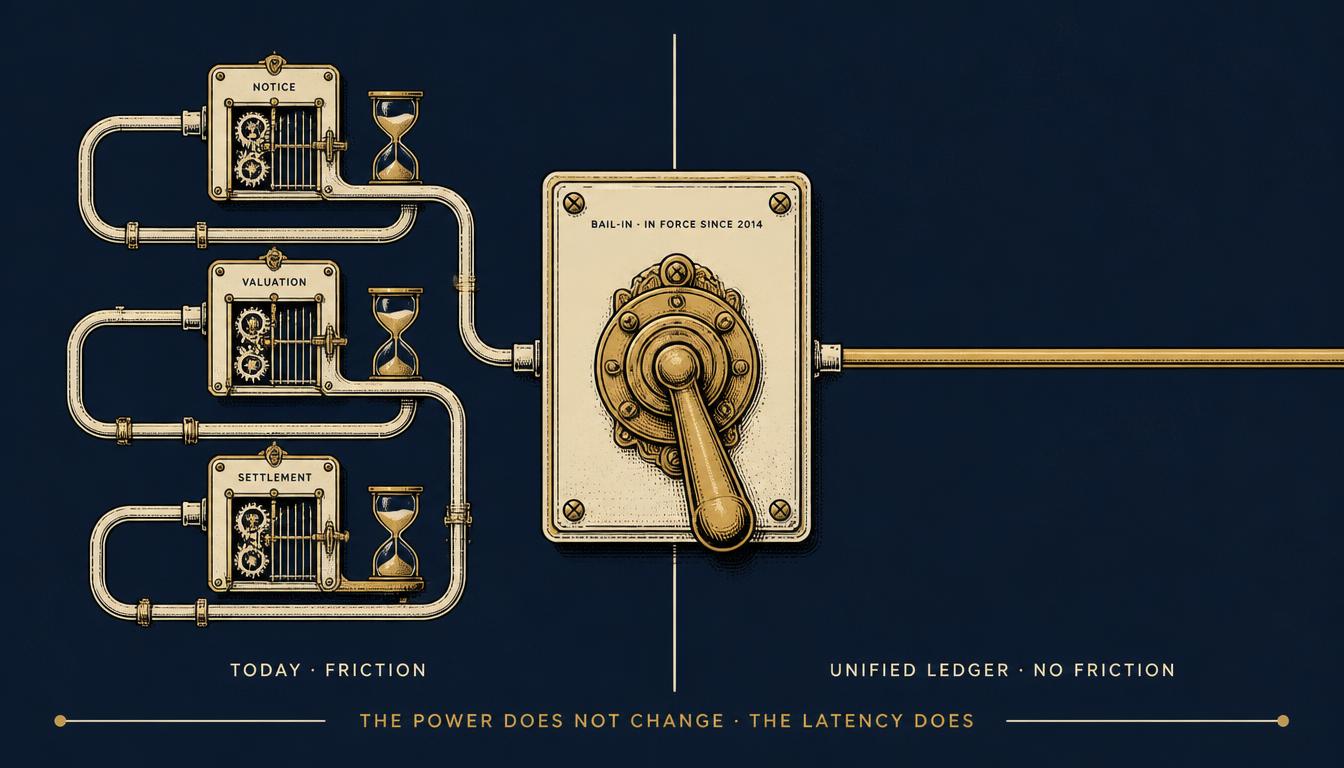
What a unified ledger would change is the latency.
Consider what executing a bail-in requires today. A resolution authority must be convened. A valuation must be performed. The creditor hierarchy must be applied to a specific balance sheet. Instructions must propagate across separate institutional systems, each with its own reconciliation, its own operating hours, its own settlement cycles. The process takes days, and conventionally it is compressed into a weekend because that is the interval during which markets are closed.
That friction was designed by no one. It is an accident of the fact that banking records live in different places and that moving a legal determination through them takes time. It protects no one deliberately. But it functions as a constraint, in three specific ways.
It bounds scope. An action requiring days of operational work across multiple institutions is practicable for one bank, difficult for several, and near-impossible for many simultaneously.
It creates an interval in which the decision is reviewable. Time between determination and execution is time in which a court can be petitioned, a political process can intervene, or the authority can reverse itself.
It makes the action visible before it completes. A weekend resolution is observable while it is happening. Depositors of other institutions can act on that information.
The architecture in question is public and specific. In June 2023 the Bank for International Settlements published Chapter III of its Annual Economic Report, titled Blueprint for the future monetary system, whose stated key elements are central bank digital currencies, tokenized deposits, and other tokenized claims, brought together in a new financial market infrastructure the Bank calls a unified ledger. The concept was extended in the 2025 report, which described a trilogy of tokenized central bank reserves, commercial bank money, and government bonds as the next logical step. It is not a leaked plan. It was published with a press release calling it game-changing, accompanied by a video and a podcast.
Within the blueprint is the sentence Forum #54 regards as the most important text in the subject: by having "everything in one place," a unified ledger provides a setting in which "a broader array of contingent actions can be automatically executed."
A bail-in is a contingent action. It is a legally defined adjustment to creditor claims, triggered by a determination that an institution is failing or likely to fail, executed according to a hierarchy specified in advance. It is precisely the class of operation that phrase describes, and nothing in the blueprint's framing excludes it. The framework is not claiming the BIS intends this. It is observing that the described capability is general, that resolution is one of the things it would be general over, and that no one drafting the blueprint would have needed to think about bail-in for that to be true.
On a ledger where central bank money, tokenized deposits, and tokenized assets share a single programmable venue with settlement finality, a creditor-hierarchy adjustment is not an operational project. It is a state change in the settlement layer. The valuation and the legal determination remain difficult — nothing about tokenization makes an institution easier to value. But the execution collapses from days to the time required to write to a ledger.
Stated as narrowly as it can be: an architecture that reduces execution latency toward zero removes a constraint on the use of an existing power, without anyone having expanded that power and without anyone needing to intend the consequence.
And the essay reports the fact that runs against the fear rather than passing over it. The Crisis Management and Deposit Insurance package, in force since May 10, 2026 and applying from May 2028, was designed specifically to let deposit guarantee funds bridge the gap so that banks can be resolved without bailing in their depositors. The direction of travel on depositor bail-in in the European Union is toward more protection, not less. But the same package lowered the public interest assessment threshold, which expands the population of institutions routed into resolution at all. Two variables moved in opposite directions, and almost no commentary has noted both.
→ Read the full analysis: Contingent Actions: What a Unified Ledger Changes About a Power That Already Exists — The Forum
Concept in Focus: Latency, Not Authority
The latency distinction generalizes well beyond resolution, and the Watching the Cracks series is largely an argument that it does.
Authority is written down. It sits in a directive, a statute, a charter, a mandate. It is discoverable by anyone willing to read the document, and hard-money commentary is generally good at finding it. Constraint is frequently not written down at all. It lives in operational friction, in reconciliation cycles, in the fact that two systems do not talk to each other, in the number of people who must sign something. Nobody defends it, because nobody designed it. It appears in no charter and is protected by no lobby.
Which means the two are removed by entirely different processes. Expanding an authority requires legislation, and legislation attracts opposition. Removing a latency constraint requires only an efficiency improvement, and efficiency improvements attract support. The first is contested in public. The second is procurement.
This is the same structural observation Forum #53 made about equity markets. Manipulation of precious metals is proven and prosecuted — JPMorgan paid $920.2 million in 2020, the largest monetary relief in the history of the Commodity Futures Trading Commission — but prosecutors established the traders moved prices both directions for trading profit, which is tactical rather than strategic. Meanwhile Gabaix and Koijen measured what happens when the marginal buyer operates under a mandate rather than a judgment: every dollar invested in the stock market raises aggregate market value by approximately five dollars, against a price elasticity near negative 0.2 where theory predicts something closer to negative 20. Before publishing, they surveyed 102 academic economists; just over half predicted no price effect whatsoever. The enormous, price-insensitive, calendar-driven bid that hard-money writers intuit is real, larger than the criminal conduct they point to, and entirely disclosed.
The framework's apparatus supplies the formulation. Forum #47 developed the Custody Depth score, which counts institutional counterparties standing between a saver and unencumbered control of an asset; a bank deposit sits at level two. Forum #45 established, following Fekete, that what functions as money in daily life is frequently a creditor position rather than money in the precise sense. A bail-in is the moment that distinction becomes operative — the event at which the claim is revealed not to be the thing, and the number is adjusted according to a hierarchy the holder never read.
The Atlas page on Money vs Currency covers the distinction underneath all of this: the difference between holding a good and holding a claim on an institution that holds a good.
The Dashboard
Snapshot from the live toolkit dashboard as of September 29, 2026.
- Mengerian Stress Index (composite) — 2.04 / elevated. PPP at −2.17σ; RHD persistent at +3.96σ; CCB Z-score at its +5 cap on a mean absolute cross-currency basis of 89.7 bps; OTROFF at −0.12σ. ENV is unavailable, so the composite runs on four of five components. → /toolkit/mengerian-stress-index
- Gold Basis (decontaminated) — +0.92% contango — spot $4,144.55 at the September 28 fix, live spot $4,176.80, COMEX /GCV26 front-month $4,182.50, basis $37.95, annualized 11.83%. Contango has compressed from +1.97% at Issue #016, and spot sits below the $4,388 recorded then. → /toolkit/gold-basis
- Silver/Gold Ratio — 68.15 — gold $4,215 futures, silver $61.85. Essentially unchanged from 67.77 at Issue #016 — the two metals have moved together across the interval rather than diverging. Silver's own front-month basis reads +0.70% contango, annualized 2.82%. → /toolkit/silver-gold-ratio
- OTROFF (10Y On/Off-the-Run Treasury Spread) — +2.51 bps, maturity-adjusted (raw +1.67, plus a +0.84 adjustment for a 92-day maturity gap), priced to the September 29 close. The on-the-run note is the August 12 auction at a 4.625% coupon yielding 5.279%; the off-the-run is the May 12 auction at 4.375% yielding 5.296%. A single-digit premium for the most-current issue is this series in its ordinary range. → /toolkit/otroff-spread
The framework's reading of the interval: the composite is carried almost entirely by two components. Repo haircut dispersion sits at +3.96σ and the cross-currency basis is at its +5 cap, the latter on a mean absolute basis of 89.7 bps across four pairs. Pulling the other way, the gold paper-physical premium reads −2.17σ as the metals hold a narrow contango. And the Treasury saleability premium is contributing essentially nothing: at +2.51 bps, the most-current ten-year note trades a fraction over an issue three months older, which is the ordinary state of that market.
The strain in this reading is a funding-market and cross-currency phenomenon, not a sovereign-saleability one. Dollar funding through the currency basis and collateral valuation in tri-party repo are both stressed; the Treasury market's own preference for the newest issue is not. Those are different failure modes with different transmission paths, and a composite reported as a single number cannot distinguish them. Forum #49 made the argument against consuming an aggregate on its face — the essay was aimed at the Bureau of Labor Statistics, and it binds the instruments on this site identically. An aggregate is only as good as the provenance of its parts, and the discipline it demands is reading the components every time, including when the number is one's own.
The Scorecard
Forum #52 marginal bondholder — supported by the auction tape. The essay's argument is that the marginal bondholder under an irredeemable standard cannot flee to a superior asset but can decline to appear at the auction, and that Treasury has stepped in to substitute for him. The auction reader carries a clean test: the same $28 billion two-year CUSIP reopened on August 26 and again on September 23. Bid-to-cover fell from 3.14 to 2.63. Indirect bidders took 26.3% down to 22.7%. Primary dealers — the buyers of last resort, obligated to bid — absorbed 72.4% rising to 75.8%. Identical paper, identical size, four weeks apart, demand deteriorating on every axis. Forum #52 records the September 23 five-year clearing at 5.033 percent, the highest since 2006, more than three basis points above expectations.
Forum #50 four calls — scored, one withdrawn. The July consumer price call was wrong on its stated terms and right on its mechanism, arriving one month late. The thirty-year Treasury threshold held decisively at 5.211 percent against a published falsification level of 4.50 percent. Gold's August behavior was the real-interest-rate mechanism from Forum #42 at unusually high resolution. And an entire segment of Episode #002 was built on a July payroll contraction of 23,000 jobs that the BLS subsequently revised to a gain of 21,000. The analysis was not merely wrong; its subject was withdrawn. No threshold was moved.
Forum #16 banking diagnostics — count now at 5 for 2026. Up from 4 at Issue #016, against a 2024–2025 baseline of two per year. The FDIC reader puts the 2026 total at five of 577 failures recorded since 2000.
Next major resolutions on the ledger: the October FOMC, first test of whether the September 16 hike to 3.75–4.00 percent begins a sequence or stands alone; Treasury's next quarterly refunding, which will show whether the buyback expansion of August 19 holds at four billion per operation or grows again; and the digital euro pilot development phase, which began in Q3 2026 ahead of a twelve-month operational pilot scheduled for the second half of 2027.
The Actionable
The framework's operational observations calibrated to Forum #54 and the interval's auction data:
- Know which side of the guarantee threshold a deposit sits on. The bail-inable category is defined by statute, not by discretion: in the European Union it is every deposit above the covered threshold, generally one hundred thousand euros per depositor per institution. The relevant question is not whether an authority would use the power. It is whether a given balance is inside or outside the category the power operates on, and that is answerable today without predicting anything.
- Apply the claim-versus-thing test before the custody test. Forum #47 established verification as a precondition to scoring Custody Depth. Forum #54 extends the same discipline one layer earlier: establish whether a holding is the asset or a claim on an institution that holds the asset, and if it is a claim, find out where it ranks. A checking balance presents as a number and is in fact a creditor position of specified priority.
- Read the composite against its components, not instead of them. The Mengerian Stress Index at 2.04 is one number standing for four, and two of those four are doing nearly all the work. A single input can move an aggregate by more than its regime bands are wide, and nothing on the face of the number says which input, or why. Any aggregate — official or the framework's own — can move for reasons unrelated to what it purports to measure, and the only defense is checking what went into it. Forum #49's argument applies to instruments on this site.
- Watch primary dealer take-up, not just clearing yields. A yield can be talked up. Dealer absorption above 75 percent on a routine reopening is the auction telling you who actually appeared.
Educational content only — not investment advice.
From the Archive
"The day of reckoning comes when capital is called upon to do what it is supposed to do: to tide over the bank during a temporary setback. The kitty is opened, and found empty."
— Antal Fekete, Falsifying Bank Balance Sheets (April 2009)
Fekete wrote this in the month the Financial Accounting Standards Board relaxed mark-to-market rules under pressure from banks and regulators, and he borrowed his title from Melchior Palyi, who had described the same practice in 1960 — banks carrying government bonds at par while the market quoted them at eight hundred dollars on the thousand, with supervisory agencies counting them as prime liquid assets regardless of maturity or price.
Fekete's subject was what happens at the moment the capital buffer is tested and found notional. He did not develop what happens next, because in 2009 the answer was a public rescue. The Bank Recovery and Resolution Directive is the codified answer to the same moment: when the kitty is opened and found empty, the hierarchy specifies who fills it, and above the guarantee threshold the depositor is on the list. Fekete diagnosed the emptiness. The directive assigns the loss. What Forum #54 adds is that the assignment is already law, and that the remaining protection is an operational delay nobody wrote down.
→ Read the full essay in the Fekete Archive
Also This Week
The seven Watching the Cracks essays published across this interval, in sequence:
- Forum #48 — Both Sides of the Cushion: AI Debt, Captive Insurers, and the Four Percent. Daniel Oliver of Myrmikan Capital traced the institutional path by which a paycheck finances the AI build-out through three channels the saver never selects. His warning concerns a number: U.S. life insurers report roughly $11.0 trillion in assets against $10.6 trillion in liabilities — an equity cushion of approximately four percent — held by an industry that owns $849 billion of the two-trillion-dollar private credit market. The essay accepts the argument and adds the half it does not reach: the cushion is measured against liabilities carried at prescribed statutory rates, and Forum #41's Law of Liabilities means a falling rate structure attacks it from the liability side simultaneously. The two failures share a trigger.
- Forum #49 — The Sign Flip: What a 44,000-Job Revision Says About Reading Aggregates. On August 7 the BLS reported July payrolls down 23,000 against a consensus expecting +83,000. On September 4 the same agency revised it to +21,000. The revision was 44,000 jobs and it reversed the sign. The sharper version of Forum #20's claim: the problem is not only what the aggregates measure but when they are believed.
- Forum #50 — Scoring the Board: Four Calls, One Revised Out of Existence. Four dated, falsifiable claims scored against the terms originally stated. See the Scorecard above.
- Forum #51 — Operation Twist Without the Fed: Treasury Buybacks and the Contested Long End. On August 19, with the long end under what one desk called a buyers' strike since late June, Treasury announced it would at least double liquidity support buybacks in the ten-to-thirty-year sectors, from $2 billion per operation to at least $4 billion. Because new issuance replaces the securities purchased, the operation does not reduce net borrowing — it shortens the duration of what the public holds. That is the economic function of the Fed's 2011–12 Maturity Extension Program, executed by the department that issues the debt, requiring no FOMC vote and operating under no dual mandate.
- Forum #52 — Three Hands on the Dial: The Contested Rate Structure and the Bondholder Who Did Not Appear. On September 16 the FOMC raised the funds rate a quarter point to 3.75–4.00 percent, the first increase since July 2023, unanimous 12–0. Four weeks earlier Treasury had doubled its buybacks. That evening the President said rates should be one percent or less. Three institutions, three positions, one variable — and following Fekete, a curve that is not a report on the price of credit but the sole instrument through which that price exists.
- Forum #53 — You Don't Need a Conspiracy When You Have Mandates. Metals manipulation partially vindicated in a form that does not support the thesis it is offered for; the Working Group on Financial Markets real, with four named members and no appropriation, no trading desk, and no documented authority to purchase securities. The manipulation frame searches for secrecy and therefore misses scale. See Concept in Focus above.
- Forum #54 — Contingent Actions — this issue's lead essay.
- Atlas: Money vs Currency — the distinction underneath a deposit that presents as money and resolves as a claim.