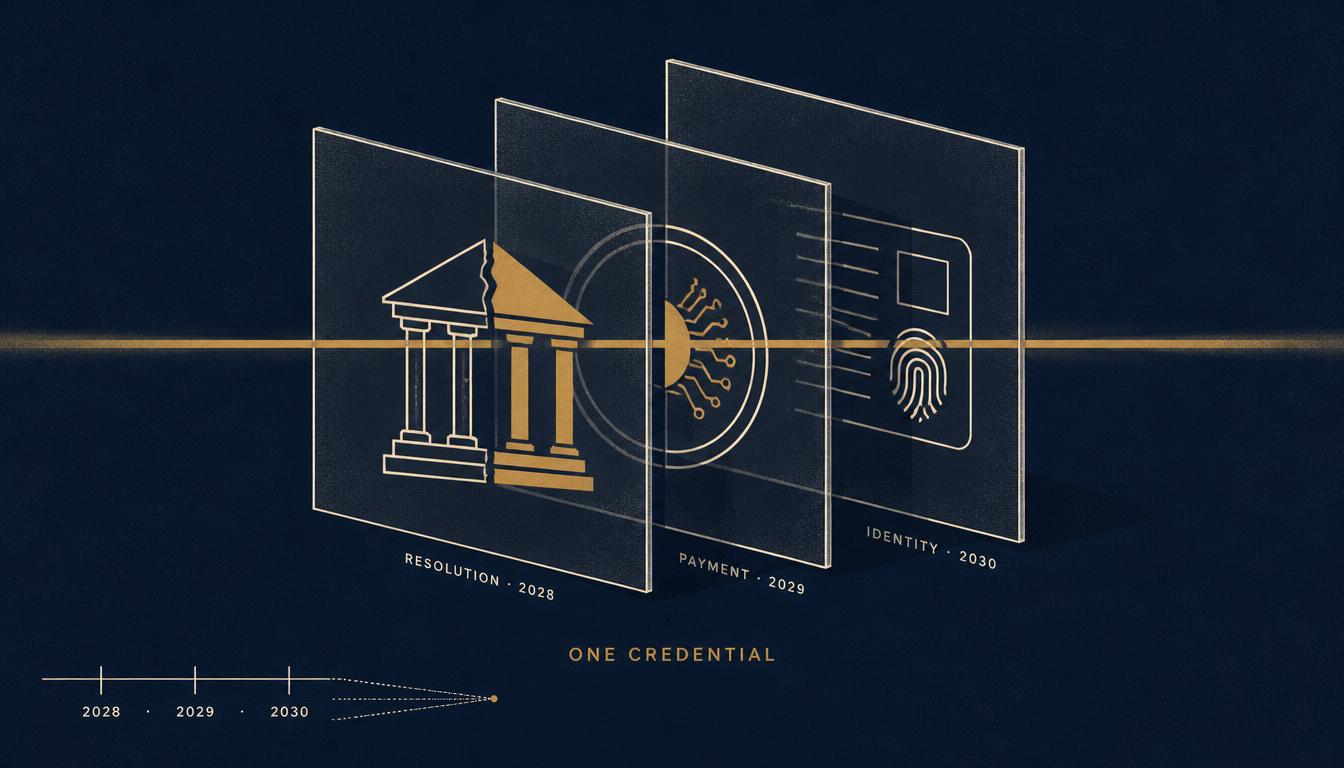
Three pieces of infrastructure are being built on published schedules that converge between 2028 and 2030. An identity layer, under Sustainable Development Goal Target 16.9 and — far sooner — Article 5a(1) of Regulation (EU) 2024/1183, which obliges every member state to provide a European Digital Identity Wallet by December 24, 2026, with mandatory private-sector acceptance twelve months later. A payment layer, in a digital euro whose twelve-month operational pilot begins in the second half of 2027 and whose potential first issuance is targeted for 2029. And a resolution layer, in the reformed Crisis Management and Deposit Insurance framework, applying from May 2028, under which deposits above the guarantee threshold remain bail-inable by statutory definition. Each was commissioned separately, by a different institution, for reasons that are individually defensible, and one of them addresses a genuine harm affecting roughly 850 million people. Forum #55 does not claim they were coordinated and finds no evidence that they were. Its claim is narrower and harder to dismiss: together they constitute an architecture in which participation, expenditure, and the adjustment of a depositor's claim all resolve to a single credential, and no document describing any one layer describes that result.
Featured essay: read the full analysis →
Researched and drafted with AI assistance · reviewed and edited by Jason D. Keys
Welcome to Issue #018 of The Dispatch. Each Monday, this letter takes one situation from the week's news and reads it through the lens of Carl Menger and Antal Fekete — paired with a foundational concept, the dashboard, the framework's prediction record, and a piece from the archive. If someone forwarded this to you, subscribe here.
The Lens
The binding date is not 2030. It is December 24, 2026 — eleven weeks from today.
Article 5a(1) of Regulation (EU) 2024/1183 requires every one of the twenty-seven member states to provide at least one European Digital Identity Wallet within twenty-four months of the relevant implementing acts. Five of those — 2024/2977 through 2024/2982 — entered into force on December 24, 2024, starting the clock. Twelve months after that deadline, in December 2027, acceptance by regulated private-sector entities becomes mandatory.
Forum #55 sets that obligation beside two others on published schedules. A payment layer: the digital euro's twelve-month operational pilot begins in the second half of 2027, with potential first issuance targeted for 2029. A resolution layer: the reformed Crisis Management and Deposit Insurance framework, in force since May 10, 2026, applies from May 2028 — and under it, as Forum #54 established, deposits above the guarantee threshold remain bail-inable by statutory definition.
Each was commissioned separately, by a different institution, for reasons that are individually defensible. The identity target addresses a documented harm: roughly 850 million people worldwide have no means to prove who they are. The essay does not claim the three were coordinated, and states plainly that the documentary record contains no evidence that they were.
The claim it does make is narrower and harder to dismiss. Together they constitute an architecture in which participation, expenditure, and the adjustment of a depositor's claim all resolve to a single credential — and no document describing any one layer describes that result.
This is the method Forum #53 and Forum #54 established, applied a third time: ask what a general capability is general over, and read the proponents' own documents rather than hunting for concealed ones.
Lead Essay: Three Layers on Published Timelines
The essay opens by discarding the wrong document. Commentary on this subject routinely points to Agenda 21, the outcome of the 1992 Rio conference. That is the wrong text — it concerns environmental management and local-authority implementation, and contains nothing resembling identity infrastructure. The operative document is the 2030 Agenda for Sustainable Development, adopted by all member states in September 2015, with its seventeen goals and 169 targets. Target 16.9 sits there, and the institutional machinery built to deliver it postdates 2015 entirely. Arguing from the 1992 document makes the case harder than it needs to be, and the record on the 2015 one is more than sufficient.
The machinery is substantial and public. A United Nations Legal Identity Agenda Task Force established in September 2018, bringing thirteen agencies together under the joint chairmanship of UNDP, UNICEF and the Department of Economic and Social Affairs. A World Bank initiative, Identification for Development, whose stated vision is "a unique legal identity and enable digital ID-based services to all." A G20 ministerial declaration naming digital identification "a basic DPI" and an entry point to Target 16.9. And a dependency structure that is easy to miss: twelve of the seventeen Sustainable Development Goals require civil registration data to measure their indicators, and 67 of 230 indicators depend on it. The identity layer is not one goal among seventeen. It is a measurement precondition for most of them.
The framework's strongest evidence is written by the proponents. The World Bank's 2016 World Development Report: Digital Dividends devotes a section to digital identity, frames the problem as 2.4 billion people lacking formal identification records, and then states the failure mode in its own text:
"A significant gap remains between technology and institutions, and where public sector accountability is low, digital technologies often help control rather than empower citizens."
That is the institution advancing the agenda, in its flagship annual report, naming the risk. The framework is not supplying a criticism from outside; it is quoting the proponent.
And the United Nations' own strategy document goes further. The Strategy for Legal Identity for All warns directly about "linking of personal information across all databases that use these identifiers," says systems should restrict use "to the extent necessary for the delivery of public services and prevent their overly intrusive use," and cautions against using identifiers "to match individuals across multiple organizations where there is no legal basis to do so."
Forum #55 draws two observations from that passage and no more. First, the linking capability is not a speculative risk raised by critics — it is a known property of the architecture, documented by the institution building it, in the strategy governing its deployment. Second, the mitigation offered is legal rather than technical. The strategy does not say the architecture cannot link records across databases. It says there should be a legal basis before it does. Those are different protections.
The payment layer requires the identity layer. A digital euro account requires identification of the holder — not a hidden provision, simply what anti-money-laundering obligations impose on any supervised payment service provider. The two are not merely contemporaneous. The second depends on the first.
And the resolution layer is where the claim becomes a claim on something. Forum #54 documented the Bank for International Settlements blueprint for a unified ledger combining central bank digital currency, tokenized deposits and tokenized assets on a single programmable platform, on the stated ground that "by having 'everything in one place', a unified ledger provides a setting in which a broader array of contingent actions can be automatically executed." A creditor-hierarchy adjustment is a contingent action.
The convergence, as the essay tabulates it: EUDI Wallet provision December 24, 2026; digital euro operational pilot H2 2027; mandatory private-sector wallet acceptance December 2027; CMDI framework applying May 2028; potential digital euro issuance 2029.
→ Read the full analysis: Three Layers, One Window: Identity, Payment, and Resolution on Published Timelines — The Forum
Concept in Focus: Provision and Acceptance
The sharpest distinction in Forum #55 is one the regulation itself does not draw, and it is worth separating out.
The obligation in Article 5a(1) runs on the state, not the citizen. Member states must provide a wallet. Nothing requires an individual to hold one. Read on its own, the text is permissive toward the person and mandatory toward the government — which is how its defenders describe it, accurately.
The thirty-six-month provision changes the balance without changing the text. From December 2027, regulated private-sector entities are obliged to accept the wallet. Consider what that means in a market where identity verification is already a precondition for opening a payment account. An instrument that every regulated counterparty must accept, in a sector where some credential is already required, does not stay one option among several. It becomes the default — not by compulsion, but by convenience on one side and obligation on the other.
The distinction between a credential one may obtain and a credential one must present in order to transact is not drawn by the regulation. It is drawn by the surrounding market.
This is the same structural observation the catalog has now made three times, and it is the reason the series keeps returning to disclosed mechanisms rather than concealed ones. Forum #53 found that mandated, calendar-driven buying moves equity prices far more than the prosecuted spoofing hard-money writers point to. Forum #54 found that bail-in authority has existed for a decade and that what a unified ledger changes is execution latency, not power. Here the finding is that nothing need be made compulsory for it to become universal. In each case the consequential mechanism is published, argued on its merits, and adopted for reasons that are mostly good — and in each case what goes unexamined is not its existence but its scope.
The Atlas page on Money vs Currency covers what sits underneath: the difference between holding a good and holding a claim on an institution that holds it. A credential is the instrument through which the second kind of holding is exercised — and, when a hierarchy is applied, adjusted.
The Dashboard
Snapshot from the live toolkit dashboard as of October 5, 2026.
- Mengerian Stress Index (composite) — 2.59 / elevated. RHD at +3.96σ; CCB Z-score at its +5 cap; PPP at +0.08σ, essentially at baseline; OTROFF at −0.04σ. ENV is unavailable, so the composite runs on four of five components. → /toolkit/mengerian-stress-index
- Cross-Currency Basis — 154.5 bps mean absolute across four pairs, pinning the component at its cap. The dispersion is the story: EUR/USD at 263.6 bps against GBP/USD 146.6, USD/CHF 141.4 and USD/JPY 66.4. Dollar funding pressure is concentrated in the euro leg. → /toolkit/cross-currency-basis
- Gold Basis — +0.035% front-to-spot, +0.56% annualized — spot $4,136.47, COMEX /GCV26 front-month $4,137.90, 23 days to delivery. The decontaminated cobasis reads +0.164% annualized, which is marginally into backwardation on the conservative bid-to-ask measure: spot bid sits above front ask. The bid/ask spread is tight and the contract is not near roll, so the reading is clean — but it is a whisker, and the curve beyond the front is still carrying normally. → /toolkit/gold-basis
- Silver Basis — +0.57%, +2.45% annualized — spot $61.03. Comfortable contango, no scarcity signal. Silver/gold ratio 67.82. → /toolkit/silver-basis
- OTROFF (10Y On/Off-the-Run Treasury Spread) — +2.86 bps, maturity-adjusted, priced to October 2. The August 12 note against the May 12 issue. An ordinary saleability premium. → /toolkit/otroff-spread
The framework's reading: the composite is carried by funding and collateral, not by the sovereign substrate or the metals. Repo haircut dispersion at +3.96σ and a cross-currency basis at its cap are both measures of what it costs to fund a position — the first in collateral terms, the second across currencies. Against that, the Treasury market's preference for its newest issue is unremarkable and the gold basis sits near its own baseline.
The concentration in EUR/USD is worth noting in a week spent reading European monetary architecture. A 263.6 bp basis on the euro leg against 66.4 on the yen is not a general dollar shortage; it is a euro-specific one. The framework records it without drawing a connection to the legislative calendar above, because none is in evidence — but the currency whose payment layer is being rebuilt on a published timetable is also the one where dollar funding is currently dearest.
The Scorecard
Forum #16 banking diagnostics — the count reaches 6. Six U.S. bank failures in 2026, against two in 2024 and two in 2025. The framework's argument in Forum #16 was that the failure count is a lagging summary of stresses visible earlier elsewhere, and that near-zero readings had historically preceded systemic events rather than indicated safety. The count has now tripled the prior two years' baseline while the FDIC reader puts 2026 sixth among the twenty-six years it tracks.
The resolution timetable is the thing to watch against it. The American failure count is rising in the same period the European Union finalizes a depositor hierarchy that applies from May 2028. These are separate jurisdictions and separate mechanisms, and the framework draws no causal line between them. What it records is that one system is producing failures at a rising rate while the other is specifying, in advance and in statute, who absorbs the loss when it does.
Forum #55's nearest testable date is eleven weeks out. December 24, 2026 is a hard obligation on twenty-seven member states to provide a certified wallet. Whether all twenty-seven meet it is a clean, dated, falsifiable test of how binding these timetables are in practice, and the framework will score it.
Next major resolutions on the ledger: the EUDI Wallet provision deadline, December 24, 2026; the October FOMC, first test of whether September's hike to 3.75–4.00 percent begins a sequence; and Q3 FDIC Quarterly Banking Profile, against a failure count now well above baseline.
The Actionable
The framework's operational observations calibrated to Forum #55:
- Read the acceptance obligation, not the provision obligation. When assessing any credential scheme, the question is not whether you are required to hold it. It is whether the parties you must transact with are required to accept it, and whether a credential is already a precondition in that market. Those two facts together determine whether something is optional in practice, and neither is usually stated in the same paragraph.
- Know which side of the guarantee threshold a deposit sits on. Unchanged from Issue #017, and it remains the single most answerable question here. The bail-inable category is defined by statute — in the European Union, every deposit above the covered threshold, generally one hundred thousand euros per depositor per institution. That is checkable today without forecasting anything.
- Distinguish legal protections from technical ones. The United Nations strategy warns against cross-database matching "where there is no legal basis to do so." That is a constraint on authorization, not on capability. A protection that depends on a legal basis persists exactly as long as the legal basis does, and the architecture it governs will outlast several legislatures.
- Verification remains the precondition for any custody arrangement. Forum #47's Verification Gate is unaffected by any of this and still comes before a Custody Depth score. Establish that the asset exists before scoring how many counterparties stand between you and it.
Educational content only — not investment advice.
From the Archive
"Most people did not even notice the subtle change. Gold coins and bank notes kept circulating as before. It was not the disappearance of gold coins from circulation that heralded the coming destruction of the world's monetary and payments system. It was the advent of legal tender."
— Antal Fekete, Monetary Reform: Gold and Bills of Exchange
Fekete is describing 1909, when the note issues of the Bank of France and the Reichsbank were made legal tender in preparation for the coming war. His point is that the decisive change was legal rather than visible. Gold coins did not vanish; the notes remained redeemable; the shop counters looked identical. What changed was that governments stopped paying civil servants in gold coin, private firms immediately followed, and the bills that were supposed to be settled at maturity in a present good began to be settled in a future one. The clearing system of the international gold standard was short-circuited before anyone could see it in a price.
The parallel Forum #55 develops is structural, not historical. The European Digital Identity Wallet does not compel a citizen to hold it. The digital euro does not abolish cash. The resolution framework does not confiscate a deposit. Each is, on its own terms, exactly what its defenders say. What changes is the surrounding obligation — who must accept what, and on what schedule — and that change happens in implementing acts and thirty-six-month clauses rather than anywhere a person transacting would encounter it. Fekete's 1909 is the framework's standing reminder that the consequential monetary changes are legal, dated, published, and almost never noticed at the counter.
→ Read the full essay in the Fekete Archive
Also This Week
- Reading #003 — The Number That No Longer Exists is out. The companion audio series continues the catalog's practice of scoring its own work, including the calls that did not survive contact with revised data.
- Forum #54 — Contingent Actions, the lead of Issue #017, is the necessary companion to this week's essay. Its argument — that bail-in authority has existed since the Bank Recovery and Resolution Directive, that the Single Resolution Board calls it the prevalent preferred strategy, and that what a unified ledger changes is execution latency rather than power — is the load-bearing claim underneath Forum #55's resolution layer.
- Forum #40 — The Delivery Mechanism documented the programmability available in central bank digital currency architectures: expiration dates, geographic restrictions, merchant category limits, purchase caps, behavior-contingent conditions, with China's digital yuan as the operational prototype. Forum #55's payment layer rests on it.
- Atlas: Money vs Currency — the distinction between a good held and a claim held, which is what a credential ultimately administers.
The Dispatch — New Austrian Economics
Get this in your inbox every Monday
Free weekly analysis through the Menger–Fekete framework. No jargon without definition.
Educational content only. Nothing in The Dispatch constitutes investment advice, financial advice, or a recommendation to buy or sell any security or asset. All analysis is provided for educational and informational purposes within the New Austrian Economics framework. Consult a qualified financial adviser before making any investment decisions.