Researched and drafted with AI assistance · reviewed and edited by Jason D. Keys
The finding
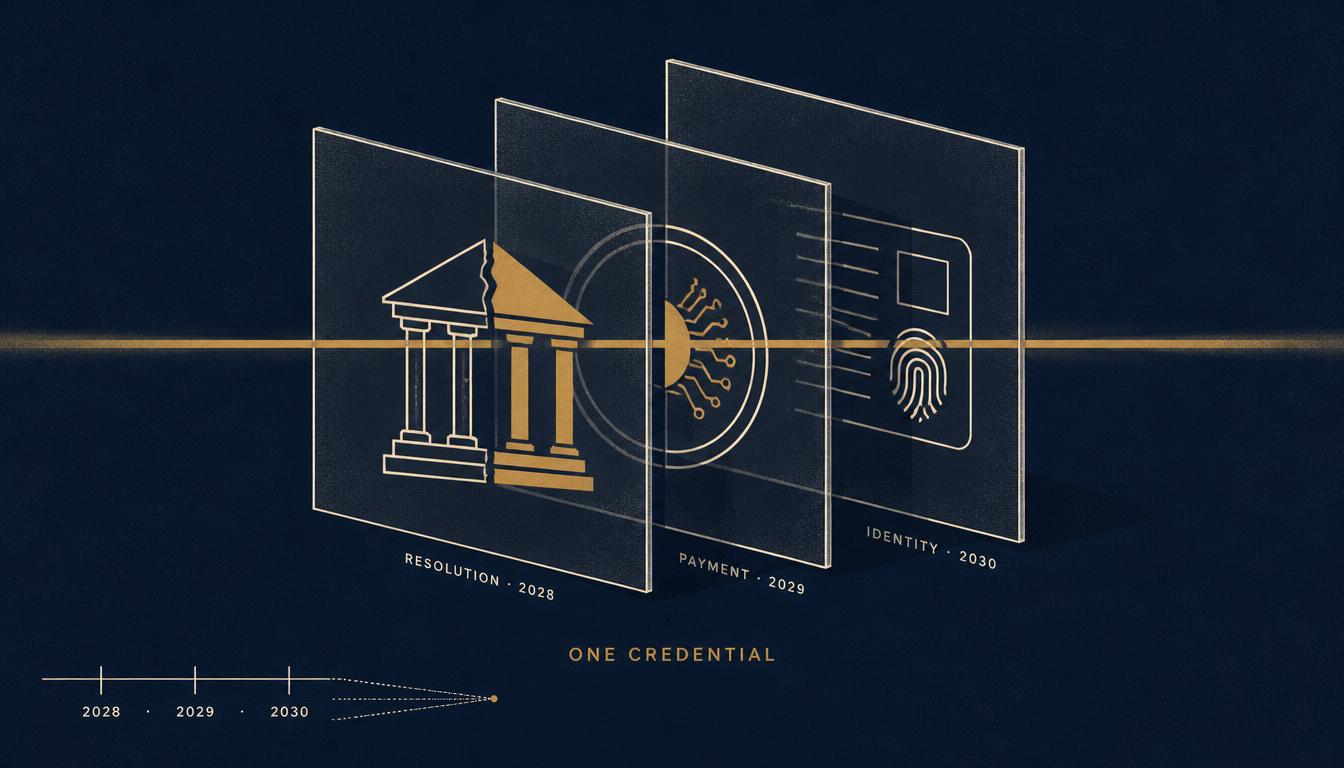
Three pieces of infrastructure are being constructed on published schedules that converge between 2028 and 2030.
An identity layer. Sustainable Development Goal Target 16.9 commits all United Nations member states to "provide legal identity for all, including birth registration" by 2030. 1 It is operationalized by a thirteen-agency United Nations task force established in 2018, 2 supported by a World Bank initiative whose stated vision is "a unique legal identity and enable digital ID-based services to all," 3 and endorsed by the G20 as "a basic DPI" — digital public infrastructure. 4
In the European Union the deadline is not 2030 but December 24, 2026. Article 5a(1) of Regulation (EU) 2024/1183 requires every member state to provide at least one European Digital Identity Wallet within twenty-four months of the relevant implementing acts, which entered into force on December 24, 2024. 5 Private-sector acceptance becomes mandatory thirty-six months after the same date — December 2027. 6
A payment layer. The digital euro's twelve-month operational pilot begins in the second half of 2027, with potential first issuance targeted for 2029. 7 Article 40 of this catalog documented the programmability of central bank digital currency architectures: expiration dates, geographic restrictions, merchant category limits, behavior-contingent conditions.
A resolution layer. The European Union's reformed Crisis Management and Deposit Insurance framework entered into force on May 10, 2026 and applies from May 2028. 8 Under it, as Article 54 of this catalog established, deposits above the guarantee threshold remain bail-inable by statutory definition. 9
Each was commissioned separately, by a different institution, for reasons that are individually defensible. The identity target addresses a documented harm: roughly 850 million people worldwide have no means to prove who they are. 10 This essay does not claim the three were coordinated, and the documentary record contains no evidence that they were.
The claim is narrower and harder to dismiss. Together they constitute an architecture in which participation, expenditure, and the adjustment of a depositor's claim all resolve to a single credential — and no document describing any one layer describes that result.
A correction on which documents matter
Commentary on this subject commonly points to Agenda 21, the outcome document of the 1992 United Nations Conference on Environment and Development. That is the wrong document, and anyone arguing from it has made the argument harder than it needs to be.
Agenda 21 is principally concerned with environmental management and local-authority implementation. It contains nothing resembling the identity infrastructure described above.
The operative document is the 2030 Agenda for Sustainable Development, adopted by all member states in September 2015, with its seventeen goals and 169 targets. 11 That is where Target 16.9 sits, and the institutional machinery built to deliver it postdates 2015 entirely.
This catalog's method requires citing what the record contains rather than what a thesis would prefer. The record on Agenda 2030 is more than sufficient.
Layer one: identity
The target. "By 2030, provide legal identity for all, including birth registration." The associated indicator, 16.9.1, measures the "proportion of children under 5 years of age whose births have been registered with a civil authority." 1
The machinery. The United Nations Legal Identity Agenda Task Force was established in September 2018, bringing together thirteen United Nations agencies under the joint chairmanship of the United Nations Development Programme, UNICEF, and the Department of Economic and Social Affairs. 2 The UNDP has stated the Task Force's working objective as ensuring that "more than 300 million people acquire a legal identity by 2025." 10
The implementation vehicle. The World Bank Group launched Identification for Development (ID4D) as a cross-practice initiative with the stated vision of "making everyone count: ensure a unique legal identity and enable digital ID-based services to all." 3
The World Bank's own assessment, in primary text. The 2016 World Development Report: Digital Dividends devotes a dedicated section — "Spotlight 4: Digital identity" — to the subject, and frames the problem in terms of scale: "digital ID systems can provide better access to public and private services for the 2.4 billion people who lack formal identification records, such as a birth certificate." 12 It records that at the time of writing, of the member states surveyed, "148 of them had some form of digital identification, and 20 had multipurpose digital identification platforms." 12
The same report contains a sentence the framework regards as the most important single line the World Bank has published on this subject:
"A significant gap remains between technology and institutions, and where public sector accountability is low, digital technologies often help control rather than empower citizens." 13
That is the institution advancing the identity agenda, in its flagship annual report, stating the failure mode. The framework is not supplying a criticism from outside. It is quoting the proponent.
The scope creep, identified contemporaneously. Privacy International observed that "the challenge in interpreting SDG 16.9 is that there is no clear definition as to what 'legal identity' means," and that the scope pursued by the implementing institutions "goes far beyond that presented in the SDG itself — 'legal identity for all, including birth registration' — to more complex forms of digital identities, and singular ID systems for the entire population." 14
The G20 endorsement. A G20 Ministerial Declaration states: "We acknowledge that digital identification, a basic DPI, can often be an entry point to digital inclusion and a mechanism to reach target 16.9 of the Sustainable Development Goals, namely to 'provide legal identity for all' by 2030." The same declaration recalls "the G20 framework on systems of DPI" and welcomes "the G20 General Principles on the Governance of Digital Identity," developed in collaboration with the OECD. 4
The dependency structure. Twelve of the seventeen Sustainable Development Goals require civil registration and vital statistics data to measure their indicators, and 67 of 230 SDG indicators depend on that data. 10 The identity layer is not one goal among seventeen. It is a measurement precondition for most of them.
The deadline is sooner than 2030
The global target is 2030. The binding European obligation is three months from this writing, and it is the most concrete element in this essay.
Regulation (EU) 2024/1183, adopted April 11, 2024 and in force since May 20, 2024, amends the original eIDAS Regulation (EU) No 910/2014 to establish the European Digital Identity Framework. 5 Its central instrument is the European Digital Identity Wallet — a mobile application in which citizens, residents, and businesses store and selectively disclose government-issued credentials.
Article 5a(1) requires each member state to "provide at least one European Digital Identity Wallet" within twenty-four months of the entry into force of the relevant implementing acts. Five implementing regulations — 2024/2977, 2024/2979, 2024/2980, 2024/2981 and 2024/2982 — were adopted November 28, 2024 and entered into force December 24, 2024, starting both the twenty-four-month and thirty-six-month clocks. 6
The resulting dates:
- December 24, 2026 — every one of the twenty-seven member states must provide at least one certified wallet. Implementing Regulation (EU) 2025/848, governing registration of wallet-relying parties, applies from the same date. 6
- December 2027 — the thirty-six-month obligation: acceptance by regulated private-sector entities becomes mandatory. 6
The European Commission's Digital Decade program separately targets 100 percent of citizens having access to digital identification by 2030, which is the same horizon as Target 16.9. 15
The framework notes two things about this. First, the obligation is on member states to provide a wallet, not on citizens to hold one — the regulation's text is permissive toward the individual and mandatory toward the state. Second, the thirty-six-month acceptance requirement changes that balance in practice: an instrument that regulated entities are obliged to accept, in a market where identity verification is already required to open a payment account, becomes the default path rather than one option among several. The distinction between a credential one may obtain and a credential one must present in order to transact is not drawn by the regulation. It is drawn by the surrounding market.
The warning in the United Nations' own strategy
The most significant document in this section is the one the implementing institution wrote about itself.
The United Nations Strategy for Legal Identity for All addresses the risk directly. It notes the danger of "linking of personal information across all databases that use these identifiers," states that systems should restrict use "to the extent necessary for the delivery of public services and prevent their overly intrusive use," and warns specifically against using such identifiers "to match individuals across multiple organizations where there is no legal basis to do so." 16
The framework draws two observations from this and no more.
First: the linking capability is not a speculative risk identified by critics. It is a known property of the architecture, documented by the institution building it, in the strategy document governing its deployment.
Second: the mitigation offered is legal rather than technical. The strategy does not say the architecture cannot link records across databases. It says there should be a legal basis before it does. Those are different protections, and the difference is the subject of the next two sections.
Layer two: payment
Article 40 of this catalog documented the programmability available in central bank digital currency architectures — expiration dates, geographic restrictions, merchant category limits, purchase amount caps, and behavior-contingent conditions — and examined China's digital yuan as the operational prototype.
The European program is now on a dated track. The European Central Bank's preparation phase ran from November 2023 to October 2025, closing with a progress report on October 30, 2025 when the Governing Council moved the project forward. 17 The call for expression of interest for pilot participants was published March 5, 2026 and closed May 14, 2026, with applicants notified at the end of June 2026. The pilot development phase began in the third quarter of 2026. A twelve-month operational pilot begins in the second half of 2027. 7 Assuming the Regulation is adopted during 2026, the Eurosystem aims to be ready for potential first issuance during 2029. 17
A digital euro account requires identification of the holder. That is not a controversial claim or a hidden provision; it follows from anti-money-laundering obligations applying to any supervised payment service provider. The identity layer and the payment layer are not merely contemporaneous. The second requires the first.
Layer three: resolution
Article 54 of this catalog established the resolution position in detail, and the relevant facts are brief.
Under the Bank Recovery and Resolution Directive, bail-in of at least eight percent of total liabilities and own funds is a precondition for accessing the Single Resolution Fund. The Single Resolution Board defines the affected category without euphemism: "Bail-inable deposits: These are all deposits with the exception of covered deposits." 9 Covered deposits are generally those up to one hundred thousand euros.
The Board's own working paper concluded that "as per the current creditor hierarchy, the DGS would be rarely able to intervene to support resolution entities falling below the 8 % TLOF without bailing-in deposits," and noted that bail-in is the prevalent preferred resolution strategy across the institutions it supervises. 9
The reformed framework entered into force May 10, 2026 and applies from May 2028. 8 As Article 54 documented, the reform moves to reduce depositor exposure by letting deposit guarantee funds bridge the gap — while simultaneously lowering the public interest assessment threshold, which expands the population of institutions routed into resolution at all.
And Article 54's central argument applies here directly: the Bank for International Settlements has published a blueprint for a "unified ledger" combining central bank digital currency, tokenized deposits, and tokenized assets on a single programmable platform, on the stated grounds that "by having 'everything in one place', a unified ledger provides a setting in which a broader array of contingent actions can be automatically executed." 18 A creditor-hierarchy adjustment is a contingent action.
The convergence, stated as fact
| Layer | Instrument | Operative date |
|---|---|---|
| Identity | EUDI Wallet — member state provision obligation, Art. 5a(1) Reg. (EU) 2024/1183 | 24 December 2026 |
| Payment | Digital euro — twelve-month operational pilot | H2 2027 |
| Identity | EUDI Wallet — mandatory private-sector acceptance (36-month obligation) | December 2027 |
| Resolution | CMDI framework (BRRD III, SRMR, DGSD) | applies May 2028 |
| Payment | Digital euro — potential first issuance | 2029 |
| Identity | SDG Target 16.9; EU Digital Decade 100% digital ID access | 2030 |
The framework states explicitly what this table is and is not.
It is not evidence of coordination. These are three workstreams, begun in different years by different institutions under different legal authorities, each with a published rationale that does not reference the others. The 2030 Agenda was adopted in 2015. The Bank Recovery and Resolution Directive predates it. The digital euro investigation began in 2021. No document in the record links them as a program.
It is a fact about the period this catalog is documenting. A reader tracking any one of these programs should know the schedules of the other two, because the implementation windows overlap and because the layers have technical dependencies on one another whether or not anyone planned them.
What a general capability is general over
This catalog's method, established across the two preceding installments, is to ask not what an institution intends but what a capability encompasses.
Article 53 applied it to market prices: no conspiracy is required to produce a non-informative price when the marginal buyer operates under a mandate, because mandates are public, uncoordinated, disclosed, and larger than any concealed scheme could be.
Article 54 applied it to resolution: a unified ledger does not create the authority to convert a depositor's claim, because that authority already exists in directive law. What it changes is the latency — removing an operational friction that was designed by no one, defends no one deliberately, and nonetheless bounds the scope, reviewability, and visibility of the action.
Applied to the three layers:
The identity layer establishes who may transact. A credential is required to open an account, and the stated target is universal coverage by 2030.
The payment layer establishes what may be purchased. Programmability permits conditions on where, when, and on what a unit may be spent — documented in Article 40, demonstrated in the digital yuan.
The resolution layer establishes what a balance is worth. The bail-in power adjusts claims according to a hierarchy set in statute, and on a unified ledger that adjustment executes as a state change rather than as a weekend of operational work.
Each capability is general. None is designed for the others. And a general capability over identity, combined with a general capability over expenditure, combined with a general capability over claim value, produces an architecture in which a person's economic existence is a function of one credential's status — without any institution having designed that, and without any document describing it.
That is not a plan. It is a convergence, and this catalog's position is that convergences of this kind are more durable than plans, because no one is responsible for them and therefore no one can be asked to stop.
Custody depth, applied to personhood
The framework's own apparatus supplies the formulation the policy literature lacks.
Article 47 developed the Custody Depth score, which counts the institutional counterparties standing between a saver and unencumbered control of an asset. Physical possession scores zero; a commodity-backed exchange-traded fund inside a retirement wrapper scores five.
The identity layer extends that measure to a prior question. Custody Depth asks how many institutions stand between a person and their property. The architecture described here raises a logically antecedent one: how many institutions stand between a person and the capacity to transact at all.
Under a cash standard, that number is zero. A banknote does not authenticate its bearer. Article 43 of this catalog documented the historical significance of that property in the specific case of sudden, undocumented flight — the one threat model in which portability dominates every other consideration, and the one in which bearer instruments proved close to uniquely protective.
Under a credential-gated payment architecture with universal coverage, the number is at least one, and the credential is issued by an authority that can suspend it. This is not a claim about intent. It is a description of what a credential is: a revocable permission, as distinct from a bearer instrument, which is a thing.
This catalog has spent fifty-four prior installments arguing that the essential discipline is distinguishing a claim from the thing it names. A digital identity credential is a claim about a person. The structure being built makes that claim a precondition for exercising claims on property — which are themselves, per Article 45, claims rather than things.
Menger, and what emergence supplies
Carl Menger's 1892 account describes money emerging from voluntary exchange through the differential saleability of commodities, without any authority selecting it. 19 The property this catalog has drawn on repeatedly is epistemic: an emergent institution carries information because it is the residue of many separate choices by parties with something at stake.
But emergence supplies a second property that is more relevant here, and the catalog has not previously named it.
An emergent monetary institution has no off switch, because no one is holding it. Gold does not authenticate its holder, cannot be revoked, and recognizes no credential. These are not features anyone designed into it; they are consequences of its being a commodity that acquired monetary function through use rather than through issuance.
A designed monetary architecture has an issuer by definition, and anything with an issuer has an administrator. Whether that administrator ever acts adversely is a question about people and politics, and this essay makes no prediction about it. Whether the capacity exists is a question about architecture, and the primary documents answer it.
What would falsify this
If the digital euro regulation prohibits conditional restrictions in its final text. The European Parliament's ECON Committee adopted its detailed position on June 23, 2026 by 43 votes to 14 with one abstention, and interinstitutional negotiations with the Council follow. 20 An explicit statutory prohibition on programmable spending conditions would directly address the payment-layer concern, and the framework would report it.
If identity requirements for digital euro holdings include a genuine anonymous tier at meaningful limits. The ECB has stated that offline functionality is planned. If the final design preserves cash-equivalent unidentified transaction capacity at non-trivial amounts, the custody-depth-over-personhood argument weakens substantially.
If the convergence of dates proves to be an artifact of selection. This remains the framework's own strongest objection to its argument, and it has been partially addressed rather than resolved. An initial draft of this essay examined three programs. A search for others with implementation dates in the same window surfaced the European Digital Identity Framework, which was missing — and which tightened the timeline rather than loosening it, moving the binding identity obligation from 2030 to December 2026. That is a case of the survey strengthening the finding, which is weaker evidence than a survey that tested it. A reader is entitled to ask what programs with dates in this window do not fit the pattern, and the framework has not cataloged those.
What would not falsify it: statements of intent. The argument concerns capability and the absence of technical constraint, and assurances about how an authority plans to behave are not evidence about what an architecture permits.
The framework's reading
The documents are public. The schedules are published. The dependencies are technical rather than conspiratorial: a digital payment account requires an identity credential because anti-money-laundering law requires it, and a resolution action executes faster on a unified ledger because that is what settlement finality on a shared platform means.
What no document contains is the composite. The 2030 Agenda does not discuss bank resolution. The Crisis Management and Deposit Insurance package does not discuss digital identity. The Bank for International Settlements blueprint discusses contingent actions in general and resolution not at all. Each institution has described its own layer accurately and has had no occasion to describe the others.
This catalog's recurring finding, now across three consecutive installments, is that the consequential mechanisms in modern finance are not concealed. They are published, argued on their merits, and adopted for reasons that are frequently good. What goes unexamined is not their existence but their composition — what happens when several general capabilities, each defensible alone, are operative in the same system at the same time.
The identity layer, the payment layer, and the resolution layer are each on published timelines converging between 2028 and 2030. That sentence contains no speculation. Every date in it is sourced to a primary document, and the framework invites correction on any of them.
Sources
Note on method. Every date and every quotation in this essay is drawn from a United Nations, World Bank, G20, European Parliament and Council, European Commission, European Central Bank, Single Resolution Board, or Bank for International Settlements document. An earlier version of this essay quoted the World Bank's 2016 World Development Report at one remove through a secondary source; that passage has been removed and replaced with language verified against the primary text at 12 and 13. The one remaining secondary citation is Privacy International at 14, used for a critical assessment rather than for a fact, and identified as such. Advocacy sources on either side of this subject have been excluded throughout.
Note on selection. The first draft of this essay examined three programs. Before publication the framework searched for other infrastructure programs with implementation dates in the same window and found the European Digital Identity Framework — Regulation (EU) 2024/1183 — which had been omitted and which materially changed the argument by moving the binding identity obligation from a 2030 global target to a December 24, 2026 legal deadline in twenty-seven member states. The essay now reflects it. The framework states plainly that this search strengthened its finding rather than testing it, and that a genuine test would require cataloging programs in this window that do not fit the pattern, which has not been done.
Framework cross-references. Article 40 (CBDC programmability — expiration dates, geographic restrictions, merchant category limits; the digital yuan as operational prototype); Article 43 (threat models and the specific protective property of bearer instruments under sudden displacement); Article 45 (the distinction between money and a creditor claim); Article 47 (the Custody Depth score); Article 53 (mandates rather than conspiracy as the operative mechanism in price formation); Article 54 (bail-in authority, the CMDI reform, and the latency argument regarding unified ledgers).
Footnotes
-
United Nations Statistics Division, Legal Identity Agenda. https://unstats.un.org/legal-identity-agenda — Source for the text of SDG Target 16.9 ("By 2030, provide legal identity for all, including birth registration"), indicator 16.9.1, the related SDG 17.19 statistical capacity target, and the UN operational definition of legal identity: "a credential, such as birth certificate, identity card or digital identity credential that is recognized as proof of legal identity under national law and in accordance with emerging international norms and principles." ↩ ↩2
-
United Nations Statistics Division, Legal Identity Agenda (as 1) — "an inter-agency coordination mechanism — the UN Legal Identity Agenda Task Force (UNLIA TF) — was established from September 2018, where 13 UN agencies, under the chairmanship of UNDP, UNICEF and the UN Department of Economic and Social Affairs, are working together to try to assist Member States achieve SDG target 16.9." ↩ ↩2
-
World Bank Group, Identification for Development (ID4D) initiative flyer, Governance Global Practice. https://www.worldbank.org/content/dam/Worldbank/Governance/GGP%20ID4D%20flyer.pdf — "Providing legal identity for all (including birth registration) by 2030 is a target shared by the international community as part of the Sustainable Development Goals (target 16.9). The World Bank Group (WBG) has launched the Identification for Development (ID4D) cross-practice initiative to help our client countries achieve this goal and with the vision of making everyone count: ensure a unique legal identity and enable digital ID-based services to all." ↩ ↩2
-
G20 Ministerial Declaration, Digital Government and Inclusive Digital Public Infrastructure section. https://dig.watch/resource/g20-ministerial-declaration — "We acknowledge that digital identification, a basic DPI, can often be an entry point to digital inclusion and a mechanism to reach target 16.9 of the Sustainable Development Goals, namely to 'provide legal identity for all' by 2030." Also the source for the recollection of "the G20 framework on systems of DPI" and the welcome of "the G20 General Principles on the Governance of Digital Identity (annex 2), developed in collaboration with the OECD." ↩ ↩2
-
Regulation (EU) 2024/1183 of the European Parliament and of the Council of 11 April 2024 amending Regulation (EU) No 910/2014 as regards establishing the European Digital Identity Framework. Adopted 11 April 2024; in force 20 May 2024. Article 5a(1) provides that each Member State "shall provide at least one European Digital Identity Wallet" within twenty-four months of the entry into force of the relevant implementing acts. Commonly referred to as eIDAS 2. European Commission overview: https://digital-strategy.ec.europa.eu/en/policies/eudi-regulation ↩ ↩2
-
Commission Implementing Regulations (EU) 2024/2977, 2024/2979, 2024/2980, 2024/2981 and 2024/2982, adopted 28 November 2024 and entered into force 24 December 2024, which start the twenty-four-month and thirty-six-month periods under Articles 5a(23) and 5c(6) of Regulation (EU) 2024/1183. The resulting member state wallet provision deadline is 24 December 2026; mandatory private-sector acceptance follows at thirty-six months, in December 2027. Implementing Regulation (EU) 2025/848, on the registration of wallet-relying parties, applies from 24 December 2026. Texts available via EUR-Lex. The European Commission's operational guidance fixes the wallet deadline at 24 December 2026. ↩ ↩2 ↩3 ↩4
-
European Central Bank, "FAQs on the digital euro pilot." https://www.ecb.europa.eu/euro/digital_euro/pilot/html/ecb.faq-digital-euro-pilot.en.html — Source for the three pilot phases: preparation in the first half of 2026 with the call for expression of interest published 5 March 2026 and closed 14 May 2026, applicants notified end of June 2026; development phase starting in the third quarter of 2026; and the twelve-month operational phase starting in the second half of 2027. ↩ ↩2
-
European Commission, "Bank recovery and resolution — Policy making timeline." https://finance.ec.europa.eu/banking/banking-regulation/bank-recovery-and-resolution_en — Entry into force of the new crisis management and deposit insurance framework on 10 May 2026; publication of Bank Recovery and Resolution Directive III in the Official Journal on 20 April 2026. For the May 2028 application date see European Commission, "A stronger framework for handling bank failures," https://finance.ec.europa.eu/publications/stronger-framework-handling-bank-failures_en ↩ ↩2
-
Single Resolution Board, "The Commission Proposal to Reform the EU Bank Crisis Management Framework: A Quantitative Assessment." SRB Working Paper Series No. 3, December 2023. https://www.srb.europa.eu/system/files/media/document/2023-12-15_Working-paper-series-3-CMDI_December-2023_0.pdf — Source for the eight percent TLOF threshold, the definition of bail-inable deposits as "all deposits with the exception of covered deposits" citing Article 44(2)(a) BRRD, the finding regarding the deposit guarantee scheme's inability to intervene without bailing in deposits, and the prevalence of bail-in as preferred resolution strategy. ↩ ↩2 ↩3
-
United Nations Development Programme, Legal Identity. https://www.undp.org/governance/legal-identity — Source for the Task Force objective that "more than 300 million people acquire a legal identity by 2025." For the figure of 850 million people worldwide lacking means to prove who they are, and for the dependency statistics (12 of 17 SDGs requiring civil registration and vital statistics data; 67 of 230 SDG indicators requiring CRVS data), see Governance4ID, "Why Good Governance of Digital ID Matters," https://www.governance4id.org/why ↩ ↩2 ↩3
-
United Nations, Transforming our world: the 2030 Agenda for Sustainable Development, adopted by the General Assembly September 2015. Seventeen goals and 169 targets. Referenced throughout the UN Legal Identity Agenda materials cited above. ↩
-
World Bank. World Development Report 2016: Digital Dividends. International Bank for Reconstruction and Development / World Bank, published 16 February 2016. ISBN 978-1-4648-0728-2. Co-Directors Deepak Mishra and Uwe Deichmann. Full text: https://documents1.worldbank.org/curated/en/896971468194972881/pdf/102725-PUB-Replacement-PUBLIC.pdf — Source for "digital ID systems can provide better access to public and private services for the 2.4 billion people who lack formal identification records, such as a birth certificate," and for the survey finding that "148 of them had some form of digital identification, and 20 had multipurpose digital identification platforms." The report contains a dedicated section, "Spotlight 4: Digital identity." Report landing page: https://www.worldbank.org/en/publication/wdr2016 ↩ ↩2 ↩3
-
World Bank, World Development Report 2016: Digital Dividends (as 12) — "A significant gap remains between technology and institutions, and where public sector accountability is low, digital technologies often help control rather than empower citizens." ↩ ↩2
-
Privacy International, "The Sustainable Development Goals, Identity, and Privacy: Does their implementation risk human rights?" https://privacyinternational.org/long-read/2237/sustainable-development-goals-identity-and-privacy-does-their-implementation-risk — Source for the observation that "there is no clear definition as to what 'legal identity' means" and that implementing institutions pursue a scope beyond the target's text. Cited for a critical assessment, not for a fact. ↩ ↩2
-
European Commission, Digital Decade policy programme — target of 100 percent of Union citizens having access to digital identification by 2030. https://digital-strategy.ec.europa.eu/en/policies/europes-digital-decade ↩
-
United Nations, United Nations Strategy for Legal Identity for All. https://unstats.un.org/legal-identity-agenda/documents/UN-Strategy-for-LIA.pdf — Source for the warnings regarding "linking of personal information across all databases that use these identifiers," restriction of use "to the extent necessary for the delivery of public services and prevent their overly intrusive use," and the caution against using identifiers "to match individuals across multiple organizations where there is no legal basis to do so." ↩
-
European Central Bank / Banque de France, "Eurosystem moving to next phase of digital euro project," 30 October 2025. https://www.banque-france.fr/en/press-release/eurosystem-moving-next-phase-digital-euro-project — Source for the conclusion of the preparation phase begun November 2023, the Governing Council decision of 30 October 2025, and the statement that assuming legislation is in place during 2026, a pilot could start in 2027 with potential first issuance during 2029. ↩ ↩2
-
Bank for International Settlements, "III. Blueprint for the future monetary system: improving the old, enabling the new." Annual Economic Report 2023, 20 June 2023. https://www.bis.org/publ/arpdf/ar2023e3.htm — "by having 'everything in one place', a unified ledger provides a setting in which a broader array of contingent actions can be automatically executed to overcome information and incentive problems." ↩
-
Menger, Carl. "On the Origins of Money." Economic Journal, Vol. 2 (1892), pp. 239–255. Translated by Caroline A. Foley. ↩
-
"Digital Euro 2026: ECB Prepares Launch as EU Lawmakers Advance Regulation." https://informedclearly.com/en/financial/57950/digital-euro-ecb-regulation-2026 — Source for the February 2026 European Parliament vote of 420 to 158, the ECON Committee position adopted 23 June 2026 by 43 votes to 14 with one abstention, and the Council's December 2025 negotiating position. ↩
Related essays
Stablecoins, CBDCs, and the Privatization of the Digital Dollar
The most important monetary fact of 2026 is not Bitcoin's quantum challenge or the on-chain housing finance buildout. It is that dollar-pegged stablecoins have become the dominant crypto-monetary instrument globally — Tether holds $141 billion in U.S. Treasuries, USDT and USDC together exceed $265 billion in circulation inside a $320 billion stablecoin market, and 43% of Sub-Saharan African crypto volume runs through stablecoins. Meanwhile, retail CBDCs have failed almost everywhere they have been deployed. The U.S. has explicitly chosen stablecoin regulation (the GENIUS Act) over a digital dollar. The framework's reading: the digital dollar layer has been privatized to Tether and Circle, and almost no one is calling this what it is.
The Hormuz Yuan Toll: A Spontaneous Mengerian Event
Iran charging yuan tolls at Hormuz during wartime, India paying for Russian crude outside the dollar, the 1974 US-Saudi economic commission expiring unreplaced — these are not geopolitical conspiracies. They are textbook Mengerian monetary evolution, happening in real time.
Monetary Power to the People
Money is a medium in McLuhan's sense — an extension of the human body that amplifies the capacity for exchange. Understanding this is the critical path to navigating the financial disruptions of the present age.