Researched and drafted with AI assistance · reviewed and edited by Jason D. Keys
What the statute does
Section 70204 of the One Big Beautiful Bill Act — Public Law 119-21 — added three new sections to the Internal Revenue Code of 1986: 530A, establishing the accounts themselves; 6434, establishing the pilot program under which the federal government makes its one-time contribution; and 128. Funding began July 5, 2026. 1
The mechanics are straightforward and worth stating precisely before the analysis begins.
Eligibility and seed. Any United States citizen under eighteen may hold an account. Children born between January 1, 2025 and December 31, 2028 with a valid Social Security number are eligible for a one-time federal contribution of $1,000 under section 6434, claimed by filing Form 4547 with an annual return. The seed does not count against the annual limit. 2 3
Contributions. Up to $5,000 per child per year for 2026 and 2027, combined across all individual contributors — parents, grandparents, relatives, friends — with inflation indexing beginning in 2028. Employers may contribute up to $2,500 per year through a qualifying program, excluded from the employee's taxable wages, and those contributions generally count toward the $5,000 limit. 4 5 Contributions by governments and tax-exempt organizations are not subject to the limit, but must be made in equal amounts to every beneficiary in a given state, geographic area, or birth year. 5 There are no income restrictions on participation.
Tax treatment and access. Contributions are after-tax, no deduction is allowed under section 219, and growth is tax-deferred. No distributions are permitted during the growth period, which runs from birth through December 31 of the year the beneficiary turns seventeen. At eighteen the account becomes an ordinary traditional IRA, subject to normal contribution limits, investment choices, and distribution rules. 6
And the investment restriction. Funds may be invested only in "eligible investments," defined by section 530A(b)(3)(A) as any mutual fund or exchange traded fund that tracks the returns of a qualified index, does not use leverage, and does not have annual fees exceeding 0.1 percent of the balance. 6 The proposed regulations state that investments "must track the returns of a broad index of equities in primarily U.S." companies. 6 No sector funds. No individual securities purchased with account funds. No cash except briefly. No self-directed option of any kind. 1
The default investment is the State Street SPDR Portfolio S&P 500 ETF. 4
That description was complete until September 30, 2026, when Treasury opened a route by which individual shares can enter a Trump Account after all — not by purchase, but by gift. The section "The donated share" below sets out those rules, which are stricter than the ones they qualify.
The sentence that matters
Set aside, for a moment, every question about whether the program is good policy. The framework's interest is in a single structural feature.
A federal statute now directs that a category of American savings may be invested in one asset class, tracking one kind of index, with no alternative the account holder may choose.
Article 53 of this catalog examined the claim, long held in hard-money commentary, that equity prices are supported by some concealed mechanism. It found the manipulation claim partially vindicated in a form that does not support the thesis — the largest proven case, JPMorgan's $920.2 million spoofing penalty, involved conduct that moved prices in both directions for trading profit — and then argued that the frame itself was the error, because searching for secrecy means missing scale.
The scale, in that essay, came from Gabaix and Koijen's measurement that every dollar invested in the stock market raises aggregate market value by approximately five dollars, with an implied demand elasticity near negative 0.2 against a theoretically expected value nearer negative 20. The mechanism, stated in their own words, is that households allocate capital to institutions "operating with a mandate to maintain a fixed equity share." 7
The essay's conclusion was that you do not need a conspiracy when you have mandates, because a mandate is public, uncoordinated, disclosed, and larger than anything concealment permits.
Trump Accounts are that argument in statute. The mandate is not a fund prospectus or an investment policy statement. It is the Internal Revenue Code, and its subjects are children who will be eighteen years from making any decision about it.
What the mandate buys
The S&P 500 is not a neutral container.
Article 46 of this catalog documented the composition: the Magnificent Seven constituted approximately thirty-four to thirty-five percent of the index by weight as of mid-2026, a figure that stood at 12.4 percent eight years earlier. The top ten holdings represent somewhere between thirty-eight and forty-one percent of index value, against roughly twenty-seven percent at the peak of the 2000 technology bubble. Nvidia alone accounted for roughly 12.7 percent.
That article stated the honest qualification and this one repeats it: the concentration is better earnings-supported than 2000, with the top ten generating about thirty-one percent of index earnings and the Magnificent Seven producing close to seventy percent of the index's economic profit. The framework does not claim this is a bubble.
What it claims is narrower. A statute directing that a child's seed capital track a broad United States equity index is, in present conditions, a statute directing roughly a third of that capital into seven correlated technology-adjacent companies — and neither the child nor the parent may choose otherwise during the eighteen years the restriction operates.
Article 48 traced the existing chain: automatic payroll deduction, into target-date and index funds selected by a plan administrator, buying that index. Eighty million workers, every two weeks. Trump Accounts extend the same chain to birth.
An estimate of the flow
The framework states its assumptions and flags this as an estimate.
Annual United States births run approximately 3.6 million. Four birth cohorts are eligible for the seed — 2025 through 2028 — giving roughly 14.4 million eligible children and a theoretical seed ceiling on the order of $14.4 billion at full claim rates, which will not be reached since the seed requires an affirmative filing.
The seed's actual uptake has run well short of that ceiling, because it requires an affirmative filing. As of March 31, 2026, the Internal Revenue Service reported that taxpayers had signed up more than four million children, of whom more than one million were covered by elections for the $1,000 contribution. 8 Against a first eligible cohort of roughly 3.6 million births, that is an election rate well under half, and at the Gabaix-Koijen central multiplier of five the elections filed to that date imply an aggregate price impact on the order of $5 billion — not the $72 billion a fully claimed seed would produce.
The account count is the number that matters, and it is no longer four million. By October 2026, Treasury reported approximately 70 million Trump Accounts created, more than 60 million of them through an auto-enrollment effort. 9 Accounts are available to every United States citizen under eighteen with a valid Social Security number, and auto-enrollment does not require a parent to do anything at all.
That is the structurally significant quantity, and it reframes the arithmetic. Seventy million accounts, each able to receive $5,000 annually from family and $2,500 from an employer, each mandated into the same index, and each locked until the beneficiary turns eighteen. The $1,000 seed is the smallest part of the program, and the affirmative-filing requirement that throttles the seed does not throttle the accounts.
The framework does not present these figures as large relative to a market capitalization in the tens of trillions. It presents them as structurally different from ordinary flows, because they are statutorily directed, price-insensitive by construction, and locked for eighteen years. A fund manager who thinks equities are expensive can hold cash. A Trump Account cannot.
The donated share
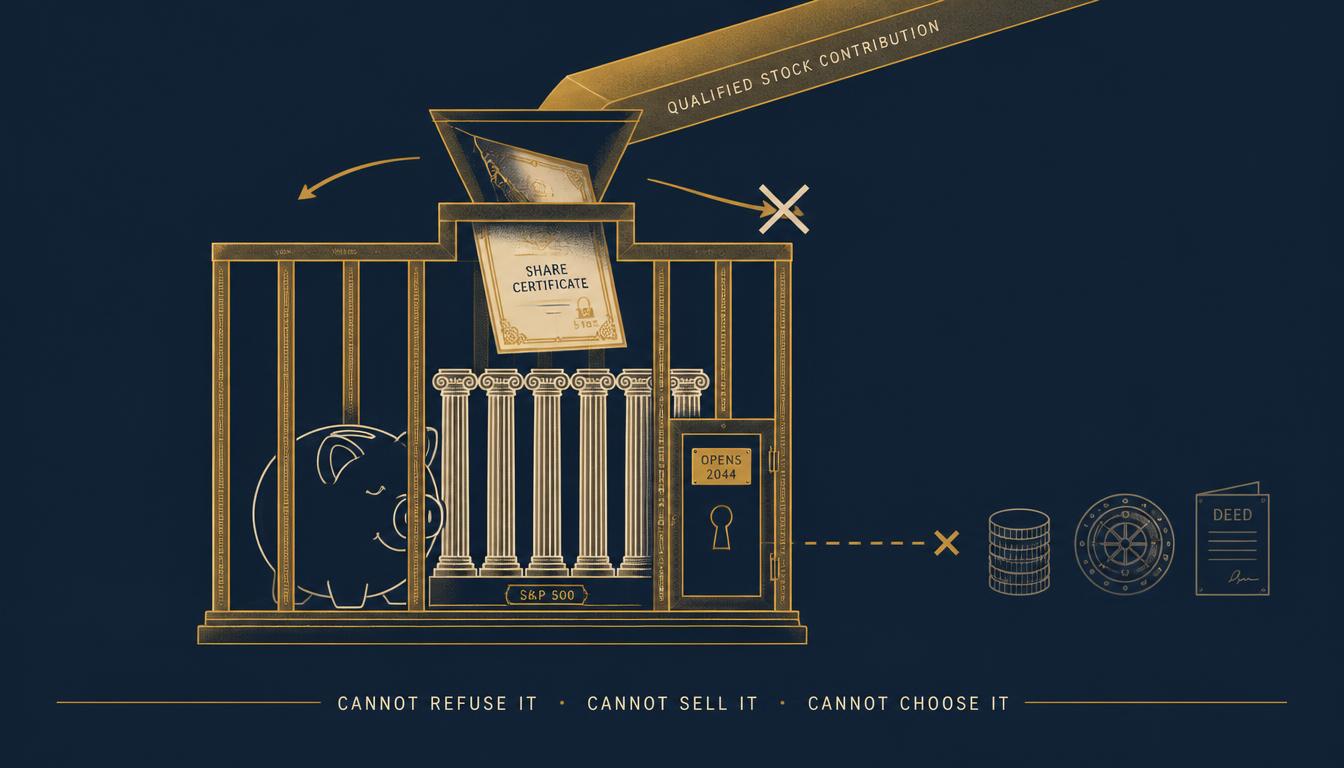
On September 30, 2026, Treasury and the Internal Revenue Service published temporary regulations — Treasury Decision 10056, codified at 26 CFR §§ 1.530A-1T and 1.530A-7T — creating a category the statute did not contemplate: the qualified stock contribution. 10
The rules are narrow in who may use them and severe in what they impose.
Who may donate. Governments, tribal entities, and organizations described in section 501(c)(3). Not parents, not grandparents, not employers. A donation must be made to a class of at least 5,000 children, and the stock must be publicly traded domestic equity. 11
Treasury's reasoning for the carve-out. The eligible-investment restriction governs what account funds may buy. Treasury concluded that holding contributed stock does not violate it because, in the regulations' own words, "no funds in the account are used to acquire the contributed stock. Rather, the stock is contributed directly into the individual Trump accounts." 10
And the terms attached to the gift. This is the part that matters.
A family cannot refuse stock gifted to a child's account. 9 The shares generally cannot be sold before the earlier of five years or the end of the calendar year in which the beneficiary turns seventeen. 9 12 And if gifted stock is disposed of improperly, the regulations require that the trustee repurchase the same number of shares of the same class "as soon as practicable." 9 Permitted early dispositions are enumerated and few: a rollover to an ABLE account, cash in lieu of fractional shares, a tender offer the responsible party directs the trustee to accept, or an acquisition or merger of the company. 12
Carolyn Schenck, an attorney and former national fraud counsel at the Internal Revenue Service, identified what the repurchase obligation reveals about whose interest the rule protects:
"If the fiduciary makes an investment mistake, then the focus is typically restoring value to the beneficiary. But here, the focus seems to be restoring the specific security itself." 9
The consequence for the child is direct. If the share price rises between an improper sale and the mandated repurchase, the beneficiary bears that cost. 9
Adam Michel, director of tax policy studies at the Cato Institute, stated the position from the family's side. Giving families more ability to hold the assets they judge best for their children would be a good thing, he said — "But this is not really that, because you have no choice in the asset that is being deposited into your child's account, and then you also have no ability to sell it for the five-year holding period." 9
The regulation's own language is the same point stated without a gloss: "the stock may not be sold before the earlier of (i) the date that is 5 years after the qualified stock contribution to the account, and (ii) the end of the growth period for the account beneficiary." 10
What this does to the essay's argument. It does not weaken it. It inverts it in a way that makes it sharper.
The preceding sections described a mandated buyer — a statute directing where a category of savings must go. The stock-donation rules create a mandated holder: an account compelled to retain a specific individual security, selected by someone else, for up to seventeen years, with a repurchase obligation if it is sold.
Article 44 of this catalog developed the forced-seller problem — the conditions under which a holder transacts at a price he would not accept if he had discretion. This is the same loss of discretion pointed in the opposite direction. The holder is not compelled to sell. He is compelled not to.
A live legal question. Practitioners have noted that a court could conclude that requiring an account to retain individual shares is itself an investment decision, and therefore contradicts the statutory eligible-investment rule rather than sitting outside it — an argument observers suggest carries more weight following the Supreme Court's overturning of Chevron deference. 13 The temporary regulations are subject to revision after public comment and expire September 30, 2029 under section 7805(e)(2). 10
The framework offers no prediction about how that resolves. It notes only that the most consequential provision governing these accounts is currently a temporary regulation with a three-year expiration, and that it was written before the pledges that made it newsworthy.
The alternatives, and their constraints
The useful question for a parent is not whether the mandate is objectionable. It is what else exists. Each alternative carries its own constraint, and naming them is the practical content of this essay.
The custodial Roth IRA. A child with earned income may fund a Roth IRA up to the lesser of earned income or the annual limit. The money grows tax-free and withdrawals of contributions are available at any time without penalty. Critically for this catalog's purposes, a Roth IRA at a self-directed custodian permits asset classes a Trump Account forbids.
The constraint is the earned income requirement, which is where the next mechanism becomes relevant.
Employing your children. A child who performs genuine work for a parent's business, at reasonable compensation for services actually rendered, has earned income. Under long-standing rules, a child under eighteen employed by a parent's sole proprietorship — or by a partnership in which both partners are the child's parents — is exempt from Social Security and Medicare taxes, and a child under twenty-one in the same structure is exempt from federal unemployment tax. The standard deduction shelters a substantial portion of that income from federal tax.
The framework states the obvious condition: the work must be real, the compensation must be reasonable, and the documentation must exist. This is a legitimate structure, not a loophole, and it fails on audit when any of those three is absent. A reader should confirm the specifics with a tax professional rather than with an essay.
What it accomplishes is the thing a Trump Account structurally cannot: it converts a child into a person with earned income, and therefore with access to a self-directed retirement vehicle.
The self-employed parent's own vehicle. Article 37 of this catalog examined the solo 401(k) with checkbook control, which permits asset classes mainstream brokerage accounts do not offer. That article's July 2026 revision and the custody correction in Article 47 established two constraints a reader must carry: allocated storage defeats custodian insolvency but not custodian fraud, and McNulty v. Commissioner, 157 T.C. No. 10 (2021), forecloses home storage of metals held inside a retirement account regardless of the entity structure used.
The UTMA custodial account. No contribution limits beyond gift-tax rules, no investment restrictions, and no purpose restriction. The constraint is control: the assets become the child's outright at the age of majority, with no mechanism for the parent to prevent whatever the child then does. For physical metal held on a child's behalf, a UTMA is the straightforward vehicle precisely because it imposes no investment mandate.
Plain physical possession. Metal held by a parent, intended for a child, inside no account at all. No tax benefit, no contribution limit, no investment restriction, no custodian, and no statutory mandate. Article 43 established that this arrangement has the distinctive property of surviving threat models that no account-based instrument survives, and Article 47 established that it carries the one risk all custodied arrangements share and that personal possession eliminates: there is no custodian to defraud anyone.
The 529, and the enrollment data
A 529 plan is the vehicle most parents compare a Trump Account against, and it deserves examination against the actual numbers rather than against either the marketing or the rhetoric.
The 529's defining feature is a purpose restriction. Qualified withdrawals for education are tax-free; non-qualified withdrawals of earnings incur income tax plus a ten percent penalty. Recent law permits rolling up to $35,000 of unused funds into the beneficiary's Roth IRA subject to conditions, which softens but does not remove the restriction.
The framework's question is whether that restriction is a bet on an institution in structural decline, and here the honest answer is more qualified than the common claim.
What the data supports. The number of American eighteen-year-olds is projected to fall approximately 13 percent between 2026 and 2041. 14 The share of high school graduates enrolling in college immediately has already declined from roughly 70 percent to 62 percent over the past decade — a behavioral shift independent of demographics. 14 Fitch Ratings anticipates "a deteriorating credit environment for U.S. Public Finance Higher Education in 2026 relative to 2025," joining Moody's and S&P in that assessment. 15 An analysis by Huron Consulting places 442 of roughly 1,700 still-operating private nonprofit colleges — more than one in four — at risk of closure or merger within ten years. 16 And Federal Reserve Bank of Philadelphia researchers, modeling a one-time fifteen percent drop in prospective students, project as many as 80 additional closures between 2025 and 2029, affecting more than 100,000 students; under a gradual decline their model yields an average of 4.6 closures a year. 17
What the data does not support. The claim that most universities will close is not supported by anything in the record. The realized rate is an order of magnitude below the rhetoric: roughly 145 closures across the whole sector from 2016 to the present, and sixteen nonprofit closures in 2025. 18 Against a historical base rate of approximately seven percent of private nonprofit four-year colleges closing between 1996 and 2023, a projection of one in four at risk over a decade is a sharp acceleration but not an extinction. 14 And the risk is concentrated rather than distributed. The institutions that have closed or merged are, in the reporting's own description, "typically been small, little known outside their home states and without endowments big enough to keep them going," many of them rural and carrying debt taken on to build facilities or simply to keep operating. 16 That is a specific category, not the sector. 19
The framework's reading. The relevant risk to a 529 holder is not that higher education disappears. It is that the purpose restriction is concentrated in exactly the institutions most at risk — small private nonprofits in the Northeast and Midwest are the category a middle-income family is most likely to be saving toward, and they are the category carrying the closure risk. A parent saving for a flagship public university faces a very different proposition from one saving for a regional private college, and the 529's tax treatment does not distinguish between them.
The deeper point is structural rather than predictive: a purpose-restricted instrument is a bet on the continued existence and continued value of the purpose. That is a different risk from market risk, it is not diversifiable within the instrument, and it is the specific thing a Trump Account does not have, since its proceeds may be used for anything once the account converts at eighteen.
Threat-modeling a child's capital
Article 43 of this catalog found that "what preserves wealth" has no single answer, and that the useful method is to name the threat model first and then select the defense that historically worked against it. The same method applies here, and it produces different answers for different parents.
If the threat is ordinary inflation over an eighteen-year horizon, and the child will likely attend a well-capitalized institution, the 529's tax treatment is genuinely valuable and the purpose restriction costs little. This is the majority case and the framework says so.
If the threat is institutional concentration risk in the equity market, the Trump Account is the worst available vehicle, because it mandates exactly the exposure in question and forbids any hedge for eighteen years. A parent in this position should take the $1,000 seed — it is free money and declining it accomplishes nothing — and direct marginal savings elsewhere.
If the threat is currency debasement specifically, Article 42's calibration analysis applies with unusual force to an eighteen-year horizon, because that is roughly the length of the 1980–2000 window in which gold lost approximately three-quarters of its real value while the monetary diagnosis remained correct throughout. A metals allocation for a child should be sized to survive that outcome, which is an argument for a bounded position rather than against a position.
If the threat is jurisdictional or custodial, Article 47's findings govern: allocated storage defeats insolvency and not fraud, retirement accounts foreclose personal possession by operation of McNulty, and the only arrangement with no custodian is the one with no tax benefit.
And if the uncertainty is about what the child will need, the purpose restriction is the variable to minimize, which argues for the Trump Account over the 529 — a conclusion the framework arrives at reluctantly, given everything else in this essay.
What the framework will not say
Three things, stated because the essay's argument is strong enough without them.
It will not say to decline the seed. One thousand dollars contributed by the federal government to a child's account is one thousand dollars. The investment mandate is a real objection to the program's design and not a reason to leave money unclaimed. A parent who objects to the mandate should take the seed, make no further contributions, and deploy marginal savings into a vehicle that permits choice.
It will not predict that the concentration ends badly. Article 46 established that today's index concentration exceeds 2000 while being better earnings-supported, and the framework has made no forecast about how it resolves. The objection here is to the absence of choice over eighteen years, not to a prediction about the asset.
It will not claim the program was designed to support equity prices. There is no evidence of that and the framework does not assert it. The design is explicable entirely as a preference for low-cost diversified investing over the alternatives available to unsophisticated holders, which is a defensible preference and probably the right default for most families. The structural consequence — a statutorily directed, price-insensitive, eighteen-year-locked flow into the most concentrated major equity index in modern history — follows regardless of intent, which is the pattern this catalog has documented repeatedly and which Article 53 named directly.
The framework's reading
The honest summary of a parent's position is that there is no unconstrained vehicle.
The Trump Account mandates the asset. The 529 mandates the purpose. The custodial Roth mandates earned income. The solo 401(k) mandates self-employment and, through McNulty, forbids personal custody of metals. The UTMA mandates relinquishing control at majority. Physical possession mandates forgoing every tax advantage.
Each is a constraint, each was adopted for a stated reason that is mostly sensible, and no vehicle combines tax treatment with investment freedom with purpose freedom with retained control. That is not an accident and it is not a conspiracy. It is what an institutional landscape looks like when each instrument was designed separately to solve one problem.
What this catalog adds is the observation it has now made in several forms: the instruments available to an ordinary saver are not neutral containers, and the constraints they impose are where the consequential decisions were already made — by a legislature, by a plan administrator, by a statute drafted before the saver was born.
In the case of a Trump Account, that last phrase is literal.
Sources
A note on the flow estimate. The figure of approximately 3.6 million annual United States births is an approximation used to produce an order-of-magnitude estimate. The theoretical ceiling assumes full claim rates, which the IRS data at 8 confirms are not being achieved, since the seed requires an affirmative filing of Form 4547. The extrapolation across four cohorts assumes the first-year election rate holds, which is an assumption rather than a finding. The Gabaix-Koijen multiplier is applied as published and the framework notes, as Article 53 did, that the multiplier is a single empirical finding rather than a settled parameter.
A note on tax structures. The discussion of employing a child in a family business describes long-standing provisions and is not individualized advice. The conditions stated — genuine work, reasonable compensation, contemporaneous documentation — are the conditions on which such arrangements are sustained or lost, and a reader should confirm specifics with a qualified tax professional before acting.
Framework cross-references. Article 44 (the forced-seller conditions, inverted here into a compelled holder); Article 37 (the 401(k) as an institutional artifact, the self-directed solo 401(k), and the Custody Depth score); Article 42 (the calibration problem and the 1980–2000 window); Article 43 (threat models and selecting a defense against a named threat); Article 46 (index concentration, the Magnificent Seven weight, and the comparison to 2000); Article 47 (allocated storage, custodian fraud, and McNulty v. Commissioner foreclosing home storage of IRA metals); Article 48 (the flow of funds from payroll deduction to index to hyperscaler equity); Article 53 (mandates rather than concealment as the operative mechanism in price formation, and the Gabaix-Koijen measurement).
Footnotes
-
Brownstein Hyatt Farber Schreck. "Baby Steps: Treasury Issues First Set of Proposed Regulations for Trump Accounts." https://www.bhfs.com/insight/baby-steps-treasury-issues-first-set-of-proposed-regulations-for-trump-accounts/ — Section 70204 of the One Big Beautiful Bill Act, Public Law 119-21, 139 Stat. 72, "added new sections 530A, 6434 and 128 to the Internal Revenue Code of 1986," with funding "beginning on July 5, 2026." Also the source for the two proposed regulations released March 6, 2026 — RIN 1545-BR91 on general account requirements and RIN 1545-BS00 on the $1,000 pilot election procedures — and for employer contributions of up to $2,500 counting toward the child's $5,000 annual limit. The investment restriction — no sector funds, no leverage, no individual securities, no sustained cash position — follows from the eligible-investment definition at 6. ↩ ↩2
-
Bipartisan Policy Center. "What to Know About Trump Accounts." https://bipartisanpolicy.org/explainer/what-to-know-about-trump-accounts/ — Source for the $1,000 pilot program contribution for United States citizen children born during calendar years 2025 through 2028, claimable at any point during the growth period from birth through December 31 of the year the beneficiary turns 17, and not counting against the $5,000 annual limit. ↩
-
Ameriprise Financial. "Trump Accounts: A guide for parents." https://www.ameriprise.com/financial-goals-priorities/personal-finance/trump-accounts — Source for the eligibility criteria, the requirement that funds track the S&P 500 or another index of equity investments primarily in United States companies with management fees capped at 10 basis points, the account opening process via IRS Form 4547 or the application at trumpaccounts.gov, and the July 4, 2026 start date for contributions. ↩
-
Empower. "Trump accounts for kids: Eligibility, government contribution, and limits." https://www.empower.com/the-currency/money/trump-account-for-kids — Source for the $5,000 annual contribution limit for 2026 and 2027, the cost-of-living adjustment provision, the automatic opening of accounts by the Treasury Department for most eligible children, the default investment in the State Street SPDR Portfolio S&P 500 ETF (SPYM), and Treasury's stated intention to add further index fund options. ↩ ↩2
-
Bipartisan Policy Center (as 2) — Source for employer contributions of up to $2,500 annually per employee counting toward the overall $5,000 limit, and for the provision that government and nonprofit contributions are not subject to the limit but must be made in equal amounts to every account beneficiary living in a given state or geographic area or born in a given year. The framework notes that published summaries differ on whether the employer limit is separate from or included within the $5,000 family limit; the majority of sources consulted treat it as counting toward. ↩ ↩2
-
KPMG. "Proposed regulations: Eligible investments for Trump accounts." 2026. https://kpmg.com/us/en/taxnewsflash/news/2026/08/proposed-regulations-eligible-investments-trump-accounts.html — Source for the statutory text of section 530A(b)(3)(A) defining eligible investments as "any mutual fund or exchange traded fund that tracks the returns of a 'qualified index,' does not use leverage, does not have annual fees and expenses of more than 0.1% of the balance of the investment in the fund"; for the growth-period restrictions including the prohibition on distributions and the denial of a section 219 deduction; and for the preamble to proposed regulations REG-117002-25, issued March 2026, stating that "investments in a Trump account must track the returns of a broad index of equities in primarily U.S." companies. ↩ ↩2 ↩3 ↩4
-
Gabaix, Xavier and Ralph S. J. Koijen. "In Search of the Origins of Financial Fluctuations: The Inelastic Markets Hypothesis." NBER Working Paper 28967, 2021. https://www.nber.org/papers/w28967 — "Households allocate capital to institutions, which are fairly constrained, for example operating with a mandate to maintain a fixed equity share… we find that investing $1 in the stock market increases the market's aggregate value by about $5." ↩
-
Internal Revenue Service, IR-2026-42, 31 March 2026. https://www.irs.gov/node/158231 — "taxpayers have signed up more than 4 million children for tax-favored Trump Accounts, of which more than 1 million children are covered by elections for the $1,000 Trump Accounts pilot program contribution." ↩ ↩2
-
Cuccinello, Hayley. "If Elon Musk gifts SpaceX stock through Trump Accounts, it will come with a catch." CNBC, published 20 October 2026, 1:10 PM EDT, updated 3:11 PM EDT. https://www.cnbc.com/2026/10/20/musk-spacex-trump-account-stock-rules.html — Carolyn Schenck, an attorney and former national fraud counsel at the IRS who left the agency in 2025 for Caplin & Drysdale: "If the fiduciary makes an investment mistake, then the focus is typically restoring value to the beneficiary. But here, the focus seems to be restoring the specific security itself." Also the source for her observation that the repurchase requirement increases beneficiaries' risk of loss if the price rises before repurchase, and that beneficiaries ultimately bear that cost. Adam Michel, director of tax policy studies at the Cato Institute: "Giving families more choices and more ability to hold the assets that they think are best for them and their kids' future … would be a good thing. But this is not really that, because you have no choice in the asset that is being deposited into your child's account, and then you also have no ability to sell it for the five-year holding period." Also the source for the provisions that families cannot refuse gifted stock and generally cannot sell before the earlier of five years or the end of the calendar year in which the beneficiary turns 17; for Treasury's citation of Michael and Susan Dell's $6.25 billion cash pledge and the acknowledgment that "It is unclear whether this level of giving can be sustained in the long run or whether it is concentrated as Trump accounts are launching"; for the Treasury statement that "Donors are attracted by the hope that a stock contribution with a five-year holding period may lead recipients and their families to feel that they have a stake in the fate of the corporation"; and for the figure of approximately 70 million Trump Accounts created, including more than 60 million through auto-enrollment. ↩ ↩2 ↩3 ↩4 ↩5 ↩6 ↩7
-
Treasury Decision 10056, RIN 1545-BS27, "Trump Accounts," temporary regulations under 26 CFR §§ 1.530A-1T and 1.530A-7T, published in the Federal Register 30 September 2026. Primary text: https://public-inspection.federalregister.gov/2026-20026.pdf — Treasury's reasoning: "Holding qualified stock received pursuant to a qualified stock contribution does not violate this restriction because no funds in the account are used to acquire the contributed stock. Rather, the stock is contributed directly into the individual Trump accounts for the beneficiaries in the designated qualified class." The minimum holding period: "the stock may not be sold before the earlier of (i) the date that is 5 years after the qualified stock contribution to the account, and (ii) the end of the growth period for the account beneficiary of that account." Also the source for expiration on 30 September 2029 pursuant to IRC section 7805(e)(2). Technical analysis at https://www.currentfederaltaxdevelopments.com/blog/2026/9/29/technical-analysis-of-treasury-decision-10056-and-proposed-regulations-cc-00226466-26-the-new-regulatory-framework-for-trump-accounts ↩ ↩2 ↩3 ↩4
-
T.D. 10056 (as 10) — Source for both the donor classes and the class-size threshold. The eligible contributors are "a State (or political subdivision thereof), the United States, the District of Columbia, an Indian Tribal government, or a section 501(c)(3) tax-exempt organization." On class size: "Section 1.530A-7T(b)(1) defines the term approved class as a class consisting of not less than 5,000 account beneficiaries," a floor the preamble says was set "to be consistent with the same minimum class size requirement reflected in the qualified geographic area requirement" of section 530A(f)(3)(B). The default investment at launch is recorded at 4. ↩
-
T.D. 10056 (as 10) — Source for the trustee repurchase obligation: "If the qualified stock is disposed of in violation of the minimum holding period requirement, the trustee must repurchase the same number of shares of the same class of qualified stock that were sold or otherwise disposed of as soon as practicable." The enumerated permitted dispositions during the holding period — a rollover to an ABLE account, cash in lieu of fractional shares, a tender offer the responsible party directs the trustee to accept, and an acquisition or merger — appear at § 1.530A-7T(d). ↩ ↩2
-
CNBC, 20 October 2026 (as 9) — Source for the legal challenge. Jane Ditelberg, chief tax strategist at Northern Trust, argued that a court could conclude that requiring an account to retain individual shares is still an investment decision, an argument that may carry more weight after the Supreme Court's overturning of Chevron deference: "These accounts are going to have to stay invested in those stocks, and the question is whether that's directly contradicting the terms of the statute. I can't tell you how a court would rule, but I could say there's room for a challenge here." Ditelberg also noted that state law grants a right to disclaim an asset and that it is unclear how the donation procedures would accommodate it. Schenck's counterpoint, from the same reporting: Treasury has broad authority to set the terms of these accounts, and it is Treasury rather than the donor that formally requires the shares to be held. ↩
-
Kelchen, Robert J., Dubravka Ritter and Douglas A. Webber. "Colleges Are Closing. Who Might Be Next?" Education Next, Vol. 25, No. 4, 25 November 2025. https://www.educationnext.org/colleges-are-closing-who-might-be-next-how-machine-learning-fill-data-gaps-forecast-future/ — "The number of American 18-year-olds is projected to fall by 13 percent between 2026 and 2041, while the share of high-school graduates enrolling in college right away has already shrunk from 70 percent to 62 percent over the last decade." The same piece records that roughly 7 percent of private nonprofit four-year colleges closed between 1996 and 2023, which is the historical base rate against which the projections below should be read. ↩ ↩2 ↩3
-
"Higher education faces 'deteriorating' 2026 outlook, Fitch says." Higher Ed Dive. https://www.highereddive.com/news/higher-education-faces-deteriorating-2026-outlook-fitch-says/807222 — For Fitch Ratings anticipating "a deteriorating credit environment for U.S. Public Finance Higher Education in 2026 relative to 2025," citing enrollment decline, new limits on federal loan programs, obstacles for international students, vulnerable state funding, and public doubt about "the value proposition of a higher education degree." Fitch projects consolidation across the sector. Moody's and S&P issued comparably negative 2026 outlooks; see https://www.highereddive.com/news/ratings-agencies-higher-ed-finance-2026-outlooks-moodys-sp-fitch-federal-policy/808596/ ↩
-
"More than a quarter of private colleges are at risk of closing, a new projection shows." The Hechinger Report. https://hechingerreport.org/more-than-a-quarter-of-private-colleges-are-at-risk-of-closing-a-new-projection-shows/ — For the finding, attributed to Peter Stokes, a managing director at Huron Consulting Group, that 442 of the nation's roughly 1,700 still-operating private nonprofit universities and colleges are at risk of having to close or merge within ten years. The reporting notes that institutions which have closed or merged have typically been small, little known outside their home states, without large endowments, often rural, and straining under debt taken on to build facilities or to continue operating. The projection is a consultancy's and is reported as such. ↩ ↩2
-
Kelchen, Robert, Dubravka Ritter and Douglas Webber. Federal Reserve Bank of Philadelphia working paper on predicting college closures, December 2024; circulated as NBER Working Paper 33216, https://ideas.repec.org/p/nbr/nberwo/33216.html — The authors build predictive models of institutional financial distress from enrollment and staffing patterns, revenue sources and liquidity. Under a scenario assuming a one-time 15 percent drop in prospective students, as many as 80 additional colleges close between 2025 and 2029, affecting more than 100,000 students and 20,880 staff. Under a gradual five-year decline, the model yields an average of 4.6 closures a year, affecting more than 7,300 students and 1,200 staff annually. ↩
-
Higher Ed Dive, "Closures and Mergers" tracker. https://www.highereddive.com/topic/closures-and-mergers — The running count of institutional closures and mergers, standing at roughly 145 from 2016 to the present, with sixteen nonprofit colleges closing in 2025. See also the parallel tracking at BestColleges, https://www.bestcolleges.com/research/closed-colleges-list-statistics-major-closures/ — Since March 2020 the two trackers together record roughly 48 public or private nonprofit institutions closed or announcing planned closure, affecting an estimated 52,600 students. ↩
-
On the concentration of risk, see Hechinger (as 16) for the profile of the institutions that have actually closed, and Kelchen, Ritter and Webber (as 14) for the 1996–2023 base rate among private nonprofit four-year institutions. The framework has not located a comparable closure series for public institutions and makes no claim about one; the point here is only that the projections at 16 and 17 are projections about private nonprofits and should not be read as sector-wide. ↩
Related essays
You Don't Need a Conspiracy When You Have Mandates
Two claims have circulated in hard-money circles for decades: that precious metals prices are systematically suppressed, and that a government body known informally as the Plunge Protection Team intervenes to support equity prices. This essay examines both against the documentary record and finds the first partially vindicated in a form that does not support the thesis it is offered for, and the second unsupported in its operative element. Manipulation of precious metals markets is proven, prosecuted, and admitted — JPMorgan paid 920.2 million dollars in 2020, the largest monetary relief in the history of the Commodity Futures Trading Commission, for conduct spanning at least eight years and hundreds of thousands of spoof orders. But prosecutors established that the traders moved prices up and down for trading profit, which is bidirectional and tactical rather than unidirectional and strategic. The Working Group on Financial Markets, established by Executive Order 12631 in March 1988, exists exactly as described, with four named members and a stated mandate — and no appropriation, no trading desk, and no documented authority to purchase securities. The essay then argues that the manipulation frame has cost the hard-money literature enormously, because it searches for secrecy and therefore misses scale. Gabaix and Koijen, in work published by the National Bureau of Economic Research, measured what happens when the marginal buyer of equities operates under a mandate rather than a judgment: every dollar invested in the stock market raises aggregate market value by approximately five dollars, against a price elasticity of demand near negative 0.2 where theory predicts something closer to negative 20. Before publishing, they surveyed 102 academic economists; just over half predicted no price effect whatsoever. The framework's conclusion is that the enormous, price-insensitive, calendar-driven bid that hard-money writers intuit is real, larger than the criminal conduct they point to, and entirely disclosed — and that Menger's account of price formation explains precisely why that is the more serious condition.
Three Answers to the Same Question: UBI, the Coasean Right, and Universal Basic Capital
On October 18, 2026, Anthropic announced it would commit five percent of its equity to a new public benefit fund held within the company. The following morning Elon Musk, who had responded to that announcement by writing that he would instead recommend giving shares directly to the public, pledged one of his SpaceX shares to every child in America. Four such pledges now stand, and commentary has reached for a label: universal basic capital. This essay sets that proposal alongside the two others this catalog has already examined — universal basic income, analyzed across the Distribution Question series, and the Coasean property right in labor-market access, examined in Article 56 — and asks the question none of the coverage asks, which is what the recipient actually ends up holding. The framework's answer is that all three converge on the same structure from different directions. Under universal basic income the recipient holds currency, which this catalog has established is a creditor claim carrying no Fourth Amendment protection and subject to programmable conditions and resolution authority. Under the Coasean right he holds a tradeable permit, which capitalizes the one asset that previously stood outside the substitute layer. And under universal basic capital delivered through the statutory channel now being discussed, he holds equity he cannot refuse, cannot sell for up to seventeen years, and cannot direct. Three proposals, three constituencies, and the same result: the recipient receives something he does not control.
The Rhetoric and the Reality: Reading the 2026 Distribution Debate
Elon Musk has endorsed 'universal high income' as the appropriate response to AI-driven displacement, putting eighty percent odds on the benign scenario in which nobody works. In May 2024 Sam Altman had already proposed 'universal basic compute' as a superior alternative to universal basic income; by August 2025 he had moved further, advocating 'universal basic wealth' and then 'universal extreme wealth for everybody.' In October 2025, the Guaranteed Income Pilot Program Act of 2025 (H.R. 5830) was introduced in the U.S. House, authorizing $495 million annually through fiscal 2030 for a three-year federal pilot. More than 150 U.S. cities now run guaranteed income programs of some kind. The rhetoric has expanded to include Peter Diamandis's 'universal basic ownership,' Mark Garman's 'universal basic capital,' 'tokenized UBI' delivered through programmable rails, and Altman's proposal to distribute one billion AI-generated tokens per person from a projected twenty quintillion annual output. The empirical picture of the displacement these proposals address is substantially more modest than the rhetoric: Goldman Sachs Research estimates 2.5 percent displacement risk in its base case and 6-7 percent under widespread adoption, resolving within about two years; the Federal Reserve projects 4.4 percent unemployment by end 2026 with no AI-driven spike; Harvard Business Review finds most AI-attributed layoffs are anticipatory, made on expected rather than demonstrated capability; and Oxford Economics finds AI cited for roughly 4.5 percent of reported job losses against four times as many attributed to ordinary market conditions. This essay is the first installment of a new framework series titled The Distribution Question. It reads the 2026 distribution debate as a specific institutional and rhetorical phenomenon: what is actually being proposed, by whom, on what empirical basis, and what the gap between the rhetoric and the reality reveals about the institutional interests that the proposals serve. Subsequent installments engage the theoretical apparatus ([Article 39](/forum/39-janus-face-marketability-distribution), on the Janus-Face of marketability) and the institutional analysis of delivery mechanisms and constructive alternatives ([Article 40](/forum/40-delivery-mechanism-positive-alternative-distribution)).